Every problem in the chapter beside the book’s answer, a chapter at a time as you scroll.

Chapter 9: Accounting for Receivables

26 problems · 1 figure

Multiple Choice 9.1 §9.1 source ↗

Which of the following is not a criterion to recognize revenue under GAAP?
  1. a.
    The earnings process must be completed.
  2. b.
    A product or service must be provided.
  3. c.
    Cash must be collected.
  4. d.
    GAAP requires that the accrual basis accounting principle be used in the revenue recognition process.

Answer

C. Cash must be collected.

Multiple Choice 9.3 §9.1 source ↗

If a customer pays with a credit card and the service has been provided, which of the following accounts will be used to record the sales entry for this transaction?
  1. a.
    Cost of Goods Sold, Merchandise Inventory, Sales Revenue
  2. b.
    Sales Revenue, Credit Card Expense, Accounts Receivable
  3. c.
    Accounts Receivable, Merchandise Inventory, Credit Card Expense
  4. d.
    Cost of Goods Sold, Credit Card Expense, Sales Revenue

Answer

B. Sales Revenue, Credit Card Expense, Accounts Receivable

Multiple Choice 9.5 §9.2 source ↗

Tines Commerce computes bad debt based on the allowance method. They determine their current year’s balance estimation to be a credit of $45,000. The previous period had a credit balance in Allowance for Doubtful Accounts of $12,000. What should be the reported figure in the adjusting entry for the current period?
  1. a.
    $12,000
  2. b.
    $45,000
  3. c.
    $33,000
  4. d.
    $57,000

Answer

C. $33,000

Multiple Choice 9.7 §9.2 source ↗

Balloons Plus computes bad debt based on the allowance method. They determine their current year’s balance estimation to be a credit of $84,000. The previous period had a credit balance in Allowance for Doubtful Accounts of $26,000. What should be the reported figure in the adjusting entry for the current period?
  1. a.
    $84,000
  2. b.
    $58,000
  3. c.
    $26,000
  4. d.
    $110,000

Answer

B. $58,000

Multiple Choice 9.9 §9.2 source ↗

Which method delays recognition of bad debt until the specific customer accounts receivable is identified?
  1. a.
    income statement method
  2. b.
    balance sheet method
  3. c.
    direct write-off method
  4. d.
    allowance method

Answer

C. direct write-off method

Multiple Choice 9.11 §9.3 source ↗

Which of the following best represents a positive product of a lower number of days’ sales in receivables ratio?
  1. a.
    collection of receivables is quick, and cash can be used for other business expenditures
  2. b.
    collection of receivables is slow, keeping cash secured to receivables
  3. c.
    credit extension is lenient
  4. d.
    the lender only lends to the top 10% of potential creditors

Answer

A. collection of receivables is quick, and cash can be used for other business expenditures

Multiple Choice 9.13 §9.3 source ↗

What information can best be elicited from a receivable ratio?
  1. a.
    company performance with current debt collection
  2. b.
    credit extension effect on cash sales
  3. c.
    likelihood of future customer bankruptcy filings
  4. d.
    an increase in future credit sales to current customers

Answer

A. company performance with current debt collection

Multiple Choice 9.15 §9.4 source ↗

Which of the following is not a way to manage earnings?
  1. a.
    Change the method for bad debt estimation.
  2. b.
    Change the figure for the uncollectible percentage.
  3. c.
    Under the balance sheet aging method, change the past-due categories.
  4. d.
    Change the dates of common stock issuance.

Answer

D. Change the dates of common stock issuance.

Multiple Choice 9.17 §9.4 source ↗

Which statement is most directly affected by a change to net income?
  1. a.
    balance sheet
  2. b.
    income statement
  3. c.
    statement of retained earnings
  4. d.
    statement of cash flows

Answer

B. income statement

Multiple Choice 9.19 §9.6 source ↗

Which of the following is true of a maturity date?
  1. a.
    It must be calculated in days, not in months or years.
  2. b.
    It is the date when principal and interest on a note are to be repaid to the lender.
  3. c.
    It is the date of establishment of note terms between a lender and customer.
  4. d.
    It is not a characteristic of a note receivable.

Answer

B. It is the date when principal and interest on a note are to be repaid to the lender.

Multiple Choice 9.21 §9.6 source ↗

A customer takes out a loan of $130,000 on January 1, with a maturity date of 36 months, and an annual interest rate of 11%. If 6 months have passed since note establishment, what would be the recorded interest figure at that time?
  1. a.
    $7,150
  2. b.
    $65,000
  3. c.
    $14,300
  4. d.
    $2,383

Answer

A. $7,150

Multiple Choice 9.23 §9.6 source ↗

Orion Rentals is unable to collect on a note worth $25,000 and has accumulated interest of $250. It convert this note and interest to accounts receivable. After some time, Orion is still unable to collect the debt and it decides to sell the converted note to a collection agency. The collection agency will pay only 20% of the value of accounts receivable to Orion. What is the amount of cash paid to Orion from the collection agency?
  1. a.
    $5,000
  2. b.
    $5,050
  3. c.
    $20,000
  4. d.
    $19,950

Answer

B. $5,050

Question 9.1 §9.1 source ↗

What is the matching principle?

Answer

The matching principle states that expenses must be matched to revenues in the period in which they were incurred.

Question 9.3 §9.1 source ↗

On January 1, a flower shop contracts with customers to provide flowers for their wedding on June 2. The total contract price is $3,000, payable in equal installments for the next six months on the first of each month (with the first payment due January 1). How much will be recorded as revenue during the month of April?

Answer

Nothing will be recognized as revenue, since the flower shop will not provide flowers until June. Until then, all revenue is considered unearned.

Question 9.5 §9.2 source ↗

Which account type is used to record bad debt estimation and is a contra account to Accounts Receivable?

Answer

Allowance for Doubtful Accounts

Question 9.7 §9.2 source ↗

Racing Adventures records bad debt using the allowance, income statement method. They recorded $134,560 in accounts receivable for the year and $323,660 in credit sales. The uncollectible percentage is 6.8%. What is the bad debt estimation for the year using the income statement method?

Answer

$22,008.88; $323,660 × 6.8%

Question 9.9 §9.2 source ↗

The following accounts receivable information pertains to Growth Markets LLC.
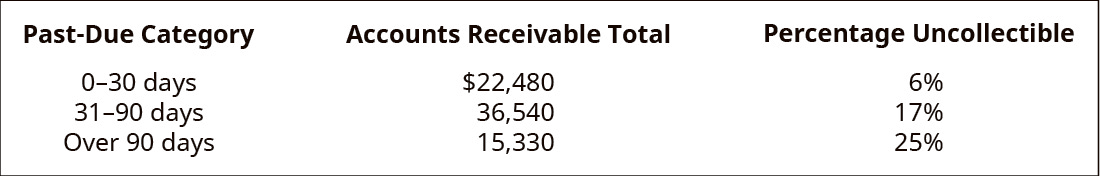
Past Due Category, Accounts Receivable Total, Uncollectible Percentage, respectively are: 0–30 days, $22,480, 6 percent; 31–90 days, 36,540, 17 percent; Over 90 days, 15,330, 25 percent.

What is the total uncollectible estimated bad debt for Growth Markets LLC?

Answer

$11,393.10; ($22,480 × 6%) + ($36,540 × 17%) + ($15,330 × 25%)

Question 9.11 §9.3 source ↗

What are some possible negative signals when the product of the accounts receivable turnover ratio is lower (i.e., fewer times)?

Answer

The receivables cycle takes a while to convert into cash, which means that cash is tied up and cannot be used for other business investments. This could also mean that the company has to borrow money from a lender to meet its cash flow demands, or that credit extensions are too tight, and good credit candidates are lost to competitors.

Question 9.13 §9.3 source ↗

What are the two most common receivables ratios, and what do these ratios tell a stakeholder about the company?

Answer

Accounts receivable turnover ratio and number of days’ sales in receivables ratio; these ratios can tell a stakeholder how credit extension policies affect sales, and how quickly current debt is collected

Question 9.15 §9.4 source ↗

What is an earnings management benefit from showing a reduced figure for bad debt expense?

Answer

A decrease to bad debt expense increases net income, which can show a higher income level and improve opportunities for borrowing.

Question 9.17 §9.4 source ↗

What is an earnings management benefit from showing an increased figure for bad debt expense?

Answer

A higher bad debt expense figure reduces net income, which could have a positive impact on reducing business income and other taxes.

Question 9.19 §9.5 source ↗

What is the installment method?

Answer

The installment method takes into account risk associated with long-term periodic payments, and it distributes revenue based on a gross profit percentage over the life of the contract.

Question 9.21 §9.5 source ↗

What is the completed contract method?

Answer

The completed contract method is used in contracts and delays reporting of both revenues and expenses until the entire contract is complete

Question 9.23 §9.6 source ↗

British Imports is unable to collect on a note worth $215,000 that has accumulated interest of $465. What is the journal entry to record the conversion of the note to accounts receivable?

Answer

Accounts Receivable 215,465  
Notes Receivable   215,000
Interest Revenue   465

Question 9.25 §9.6 source ↗

What is the principal of a note?

Answer

The principal of a note is the initial borrowed amount, not including interest, requested by the customer.

Question 9.27 §9.6 source ↗

What are three differences between accounts receivable and notes receivable?

Answer

Accounts receivable is an informal, short-term payment and usually no interest, whereas notes receivable is a legal contract, long-term payment, and usually has interest.

Loading chapter 10…

Problems and answers are adapted from Principles of Accounting, Volume 1: Financial Accounting by Mitchell Franklin, Patty Graybeal and Dixon Cooper, OpenStax, and are used under the CC BY-NC-SA 4.0 licence. Access for free at https://openstax.org/books/principles-financial-accounting/pages/1-why-it-matters. Illustrations: Copyright Rice University, OpenStax, under CC BY-NC-SA 4.0 license. This adaptation is released under the same licence, is non-commercial, and is neither affiliated with nor endorsed by OpenStax or Rice University.