Every problem in the chapter beside the book’s answer, a chapter at a time as you scroll.
Chapter 6: Money Management
286 problems · 25 figuresYour Turn 6.1 §6.1 source ↗
Rewrite the following as fractions:
3%Answer
To write n% in its fractional form is to write the percent as the fraction .
Your Turn 6.1 (b) §6.1 source ↗
Rewrite the following as fractions:
94%Answer
To write n% in its fractional form is to write the percent as the fraction .
Your Turn 6.1 (c) §6.1 source ↗
Rewrite the following as fractions:
67.2%Answer
To write n% in its fractional form is to write the percent as the fraction .
Your Turn 6.1 (d) §6.1 source ↗
Rewrite the following as fractions:
670%Answer
To write n% in its fractional form is to write the percent as the fraction .
Your Turn 6.2 §6.1 source ↗
Convert the following percents to decimal form:
9%Answer
The decimal form of n% is found by calculating the decimal value of n ÷ 100.
9% is 9 divided by 100.
This moves the decimal point two places to the left, resulting in 0.09.
0.09Your Turn 6.2 (b) §6.1 source ↗
Convert the following percents to decimal form:
24%Answer
The decimal form of n% is found by calculating the decimal value of n ÷ 100.
24% is 24 divided by 100.
This moves the decimal point two places to the left, resulting in 0.24.
0.24Your Turn 6.2 (c) §6.1 source ↗
Convert the following percents to decimal form:
2.18%Answer
The decimal form of n% is found by calculating the decimal value of n ÷ 100.
2.18% is 2.18 divided by 100.
This moves the decimal point two places to the left, resulting in 0.0218.
0.0218Your Turn 6.3 §6.1 source ↗
Convert the following to percent:
0.41Answer
To convert the number x from decimal form to percent, multiply x by 100 and place a percent sign, %, after the number: .
41%
Your Turn 6.3 (b) §6.1 source ↗
Convert the following to percent:
0.02Answer
To convert the number x from decimal form to percent, multiply x by 100 and place a percent sign, %, after the number: .
2%
Your Turn 6.3 (c) §6.1 source ↗
Convert the following to percent:
9.2481Answer
To convert the number x from decimal form to percent, multiply x by 100 and place a percent sign, %, after the number: .
924.81%
Your Turn 6.4 §6.1 source ↗
Answer
The formula relating the total (base), the percent in decimal form, and the part (amount) is
or .
26% of 1,300
338
Your Turn 6.4 (b) §6.1 source ↗
Answer
The formula relating the total (base), the percent in decimal form, and the part (amount) is
or .
225% of 915
2058.75
Your Turn 6.5 §6.1 source ↗
Answer
The formula relating the total (base), the percent in decimal form, and the part (amount) is
.
45 is 18% of the total.
The total is 250.
250Your Turn 6.5 (b) §6.1 source ↗
Answer
The formula relating the total (base), the percent in decimal form, and the part (amount) is
.
900 is 15% of the total.
The total is 6,000.
6,000Your Turn 6.6 §6.1 source ↗
Find the percent in the following:
Total is 40, percent of the total is 25Answer
The formula relating the total (base), the percent in decimal form, and the part (amount) is
.
25 is what percent of 40?
To convert the number x from decimal form to percent, multiply x by 100 and place a percent sign, %, after the number: (x × 100)%.
0.625 = 62.5%
62.5%Your Turn 6.6 (b) §6.1 source ↗
Find the percent in the following:
Total is 730, percent of the total is 292Answer
The formula relating the total (base), the percent in decimal form, and the part (amount) is
.
292 is what percent of 730?
To convert the number x from decimal form to percent, multiply x by 100 and place a percent sign, %, after the number: (x × 100)%.
0.40 = 40%
40%Your Turn 6.7 §6.1 source ↗
Answer
The formula relating the total (base), the percent in decimal form, and the part (amount) is
or .
30% of $1,765
The amount is $529.50.
$529.50Your Turn 6.8 §6.1 source ↗
Answer
The formula relating the total (base), the percent in decimal form, and the part (amount) is
.
1,679 is what percent of 2,532?
To convert the number x from decimal form to percent, multiply x by 100 and place a percent sign, %, after the number: (x × 100)%.
0.6631 = 66.31%
66.31%Your Turn 6.9 §6.1 source ↗
Answer
The formula relating the total (base), the percent in decimal form, and the part (amount) is
.
52 is 65% of the total.
The total is 80 bulbs.
80 bulbs.Check Your Understanding 6.1.1 §6.1 source ↗
Answer
To write n% in its fractional form is to write the percent as the fraction .
100
100Check Your Understanding 6.1.2 §6.1 source ↗
Answer
The decimal form of n% is found by calculating the decimal value of n ÷ 100.
38.7% is 38.7 divided by 100.
This moves the decimal point two places to the left, resulting in 0.387.
0.387Check Your Understanding 6.1.3 §6.1 source ↗
Answer
The formula relating the total (base), the percent in decimal form, and the part (amount) is
or .
68% of 280
190.4
Check Your Understanding 6.1.4 §6.1 source ↗
Answer
The formula relating the total (base), the percent in decimal form, and the part (amount) is
.
342 is 41% of the total.
The total is approximately 834.15 (rounded to two decimal places).
834.15 (rounded to two decimal places)Check Your Understanding 6.1.5 §6.1 source ↗
Answer
The formula relating the total (base), the percent in decimal form, and the part (amount) is
.
80,000,000 is what percent of 332,403,650?
To convert the number x from decimal form to percent, multiply x by 100 and place a percent sign, %, after the number: (x × 100)%.
≈ 24.07% (an approximation)
24.07%Check Your Understanding 6.1.6 §6.1 source ↗
Answer
The formula relating the total (base), the percent in decimal form, and the part (amount) is
or .
What is 20% of 80?
Amazon needs 16 more drivers.
16 new drivers will be hired.Your Turn 6.10 §6.2 source ↗
Calculate the discount for the given original price and discount percentage. Then calculate the sale price.
Original price = $1,550.00; percent discount is 32%Answer
discount = percent discount × original price
sale price = original price – discount
sale price = 1,550 – 496 = $1,054
The discount is $496 and the sale price is $1,054.
Discount is $496; sale price is $1,054.00Your Turn 6.10 (b) §6.2 source ↗
Calculate the discount for the given original price and discount percentage. Then calculate the sale price.
Original price = $27.50; percent discount is 10%Answer
discount = percent discount × original price
sale price = original price – discount
sale price = 27.50 – 2.75 = $24.75
The discount is $2.75 and the sale price is $24.75.
Discount is $2.75; sale price is $24.75Your Turn 6.11 §6.2 source ↗
Determine the percent discount based on the given original and sale prices.
Original price = $250.00; sale price = $162.50Answer
sale price = original price – discount
162.50 = 250 – discount
discount = 87.50
87.50 is what percent of 250?
87.50 = percent discount × 250
The percent discount is 35%.
Your Turn 6.11 (b) §6.2 source ↗
Determine the percent discount based on the given original and sale prices.
Original price = $19.50; sale price = $17.16Answer
sale price = original price – discount
17.16 = 19.50 – discount
discount = 2.34
2.34 is what percent of 19.50?
2.34 = percent discount × 19.50
The percent discount is 12%.
Your Turn 6.12 §6.2 source ↗
Determine the original price based on the percent discount and sale price.
Percent discount 15%; sale price = $11.05Answer
If the percent discount was 15%, the sale price is 85% of the original price.
sale price = original price × (1 – percent discount)
The original price was $13.
Your Turn 6.12 (b) §6.2 source ↗
Determine the original price based on the percent discount and sale price.
Percent discount 9%; sale price = $200.20Answer
If the percent discount was 9%, the sale price is 91% of the original price.
sale price = original price × (1 – percent discount)
The original price was $220.
Your Turn 6.13 §6.2 source ↗
Answer
discount = percent discount × original price
discount = 0.60 × 550 = $330
sale price = original price – discount
sale price = 550 – 330 = $220
The discount is $330 and the sale price is $220.
Discount is $330; sale price of the bed is $220.Your Turn 6.14 §6.2 source ↗
Answer
sale price = original price – discount
13.43 = 15.80 – discount
discount = 2.37
2.37 is what percent of 15.80?
2.37 = percent discount × 15.80
= percent discount
0.15 = percent discount
The percent discount is 15%.
15%Your Turn 6.15 §6.2 source ↗
Answer
100% – 26% = 74%
If the percent discount was 26%, the sale price is 76% of the original price.
sale price = original price × (1 – percent discount)
The original price was $59.
$59.00Your Turn 6.16 §6.2 source ↗
Calculate the markup for the given cost and markup percentage. Then calculate the retail price.
Cost = $1,800.00; percent markup is 22%Answer
markup = percent markup × cost
markup = 0.22 × $1,800
markup = $396
retail price = cost + markup
retail price = 1,800 + 396 = $2,196
Markup is $396; retail price is $2,196.00.Your Turn 6.16 (b) §6.2 source ↗
Calculate the markup for the given cost and markup percentage. Then calculate the retail price.
Cost = $10.50; percent markup is 10%Answer
markup = percent markup × cost
markup = 0.10 × $10.50
markup = $1.05
retail price = cost + markup
retail price = 10.50 + 1.05 = $11.55
Markup is $1.05; retail price is $11.55.Your Turn 6.17 §6.2 source ↗
Determine the percent markup based on the given cost and retail price. Round percentages to two decimal places.
Cost = $120.00; retail price = $190.00Answer
retail price = cost + markup
190 = 120 + markup
70 = markup
The markup is what percent of cost?
70 is what percent of 120?
70 = percent markup × 120
= percent markup
0.5833 ≈ percent markup
58.33% ≈ percent markup
58.33%Your Turn 6.17 (b) §6.2 source ↗
Determine the percent markup based on the given cost and retail price. Round percentages to two decimal places.
Cost = $0.38; retail price = $1.14Answer
retail price = cost + markup
1.14 = 0.38 + markup
0.76 = markup
The markup is what percent of cost?
0.76 is what percent of 0.38?
0.76 = percent markup × 0.38
= percent markup
2 = percent markup
200% = percent markup
200%Your Turn 6.18 §6.2 source ↗
Determine the cost based on the percent markup and retail price.
Percent markup 15%; retail price = $40.25Answer
retail price = cost × (1 + percent markup)
| 40.25 = cost × (1 + 0.15) | |
| 40.25 = cost × (1.15) | Divide by 1.15. |
| $35 = cost |
Your Turn 6.18 (b) §6.2 source ↗
Determine the cost based on the percent markup and retail price.
Percent markup 300%; retail price = $35.96Answer
retail price = cost × (1 + percent markup)
| 35.96 = cost × (1 + 3.00) | |
| 35.96 = cost × (4) | Divide by 4. |
| $8.99 = cost |
Your Turn 6.19 §6.2 source ↗
Answer
markup = percent markup × cost
markup = 2.50 × 360
markup = 900
retail price = cost + markup
retail price = 360 + 900 = $1,260
The retail price is $1,260.
The retail price of the bed is $1,260.00.Your Turn 6.20 §6.2 source ↗
Answer
retail price = cost + markup
| 234.36 = 189 + markup | Subtract 189. |
45.36 = markup
The markup is what percent of cost?
45.36 is what percent of 189?
45.36 = percent markup × 189
= percent markup
0.24 = percent markup
24% = percent markup
The percent markup is 24 percent.
24%Your Turn 6.21 §6.2 source ↗
Answer
retail price = cost × (1 + percent markup)
| 57 = cost × (1 + 0.50) | |
| 57 = cost × (1.5) | Divide by 1.5. |
| $38 = cost | |
| Tina’s cost is $38. |
Your Turn 6.22 §6.2 source ↗
The sales tax in Union County, Oregon, is 7%. Find the sales tax and total price of items based on the purchase price listed.
Purchase price = $1,499.00Answer
sales tax = purchase price × tax rate
sales tax = 1,499 × 0.07
sales tax = $104.93
total price = purchase price + sales tax = 1,499 + 104.93 = $1,603.93
The sales tax is $104.93 and the total price is $1,603.93.
Sales tax is $104.93; total price is $1,603.93.Your Turn 6.22 (b) §6.2 source ↗
The sales tax in Union County, Oregon, is 7%. Find the sales tax and total price of items based on the purchase price listed.
Purchase price = $26.89Answer
sales tax = purchase price × tax rate
sales tax = 26.89 × 0.07
| sales tax = $1.88 | (rounded to the nearest cent) |
total price = purchase price + sales tax = 26.89 + 1.88 = $28.77
The sales tax is $1.88 and the total price is $28.77.
Sales tax is $1.88; total price is $28.77.Your Turn 6.23 §6.2 source ↗
Find the sales tax rate for the indicated purchase price and total price. Round using the guideline for sales tax percentages.
Purchase price = $83.90; total price = $88.30Answer
total price = purchase price + sales tax
88.30 = 83.90 + sales tax
$4.40 = sales tax
sales tax = purchase price × tax rate
4.40 = 83.90 × tax rate
tax rate
0.052443… ≈ tax rate
The tax rate is approximately 5.24%.
Sales tax rate = 5.25%Your Turn 6.23 (b) §6.2 source ↗
Find the sales tax rate for the indicated purchase price and total price. Round using the guideline for sales tax percentages.
Purchase price = $477.00; total price = $509.20Answer
total price = purchase price + sales tax
509.20 = 477 + sales tax
$32.20 = sales tax
sales tax = purchase price × tax rate
32.20 = 477 × tax rate
tax rate
0.0675 ≈ tax rate
The tax rate is approximately 6.75%.
Sales tax rate = 6.75%Your Turn 6.24 §6.2 source ↗
Find the purchase price for the indicated sales tax rate and total price.
Sales tax rate = 8.25%; total price = $157.81Answer
total price = purchase price × (1 + tax rate)
157.81 = purchase price × (1 + 0.0825)
157.81 = purchase price × (1.0825)
= purchase price
| $145.78 ≈ purchase price | (rounded to the nearest cent) |
Your Turn 6.24 (b) §6.2 source ↗
Find the purchase price for the indicated sales tax rate and total price.
Sales tax rate = 6.75%; total price = $522.01Answer
total price = purchase price × (1 + tax rate)
522.01 = purchase price × (1 + 0.0675)
522.01 = purchase price × (1.0675)
= purchase price
| $489.00 ≈ purchase price | (rounded to the nearest cent) |
Your Turn 6.25 §6.2 source ↗
Answer
sales tax = purchase price × tax rate
sales tax = 1,149 × 0.0968
| sales tax = $111.22 | (rounded to the nearest cent) |
total price = purchase price + sales tax = 1,149 + 111.22 = $1,260.22
Daryl’s sales tax is $111.22. The total price is $1,260.22.
Sales tax is $111.22. The total price Daryl pays is $1,260.22.Your Turn 6.26 §6.2 source ↗
Answer
total price = purchase price × (1 + tax rate)
153 = purchase price × (1 + 0.0625)
153 = purchase price × (1.0625)
= purchase price
$144 = purchase price
total price = purchase price + sales tax
153 = 144 + sales tax
$9 = sales tax
The sales tax is $9.
The sales tax is $9.Check Your Understanding 6.2.7 §6.2 source ↗
Answer
Check Your Understanding 6.2.8 §6.2 source ↗
Answer
Check Your Understanding 6.2.9 §6.2 source ↗
Answer
discount = percent discount × original price
discount = 0.32 × 45 = $14.40
sale price = original price – discount
sale price = 45 – 14.40 = $30.60
The price after the discount is $30.60.
$30.60Check Your Understanding 6.2.10 §6.2 source ↗
Answer
markup = percent markup × cost
markup = 0.60 × $311
markup = $186.60
retail price = cost + markup
retail price = 311 + 186.60 = $497.60
The price after the markup is $497.60.
$497.60Check Your Understanding 6.2.11 §6.2 source ↗
Answer
Yes.
This pair of formulas mirrors each other.
retail price = cost + markup
total price = purchase price + sales tax
This is another pair of formulas:
markup = percent markup × cost
sales tax = purchase price × tax rate
YesCheck Your Understanding 6.2.12 §6.2 source ↗
Answer
sales tax = purchase price × tax rate
sales tax = 39.95 × 0.068
| sales tax = $2.72 | (rounded to the nearest cent) |
total price = purchase price + sales tax = 39.95 + 2.72 = $42.67
The total price is $42.67.
$42.67Your Turn 6.27 §6.3 source ↗
Calculate the simple interest to be paid on a loan with the given principal, annual percentage rate, and number of years. Then calculate the loan payoff, or total to be repaid.
Principal = $6,700, annual interest rate = 11.99%, and number of years = 3Answer
The interest is $2,409.99.
The loan payoff is the sum of the principal and the interest.
Interest = $2,409.99, the loan payoff is $9,109.99
Your Turn 6.27 (b) §6.3 source ↗
Calculate the simple interest to be paid on a loan with the given principal, annual percentage rate, and number of years. Then calculate the loan payoff, or total to be repaid.
Principal = $25,800, annual interest rate = 6.9%, and number of years = 5Answer
The interest is $8,901.
The loan payoff is the sum of the principal and the interest.
Interest = $8,901, the loan payoff is $34,701.00
Your Turn 6.28 §6.3 source ↗
Answer
The interest is $878.75.
The loan payoff is the sum of the principal and the interest.
The total repayment is $10,378.75.
She will pay $878.75 in interest, total repayment is $10,378.75.Your Turn 6.29 §6.3 source ↗
Answer
Remember that 6 months is 0.5 years.
The interest is $727.86.
The loan payoff is the sum of the principal and the interest.
The payoff is $9,127.86.
He will pay $727.86 in interest, payoff is $9,127.86.Your Turn 6.30 §6.3 source ↗
Answer
Remember that 60 days is years.
The interest is $115.51 (rounded to the nearest cent; interest is usually rounded up when paid to the lender).
The loan payoff is the sum of the principal and the interest.
The loan payoff is $3,815.50.
The cost to borrow is $115.51 and their payoff is $3,815.51.Your Turn 6.31 §6.3 source ↗
In the following, determine how much interest was earned on the investment and the future value of the investment if the investment yields simple interest.
Principal is $4,500, annual interest rate is 1.88%, and time is 3 yearsAnswer
Interest = $253.8, = $4,753.80
Your Turn 6.31 (b) §6.3 source ↗
In the following, determine how much interest was earned on the investment and the future value of the investment if the investment yields simple interest.
Principal is $2,000, annual interest rate is 2.03%, and time is 10 yearsAnswer
Interest = $406.00, = $2,406.00
Your Turn 6.31 (c) §6.3 source ↗
In the following, determine how much interest was earned on the investment and the future value of the investment if the investment yields simple interest.
Principal is $120,000, annual interest rate is 3.1%, and time is 100 daysAnswer
Interest= $1019.18, = $121,019.18
Your Turn 6.31 (d) §6.3 source ↗
In the following, determine how much interest was earned on the investment and the future value of the investment if the investment yields simple interest.
Principal is $4,680, annual interest rate is 1.55%, and time is 42 monthsAnswer
Interest = $253.89, = $4,933.89
Your Turn 6.32 §6.3 source ↗
Answer
Mia will receive $6,254.85.
Your Turn 6.33 §6.3 source ↗
Answer
| (rounded to the nearest cent) |
Your Turn 6.33 (b) §6.3 source ↗
Answer
| (rounded to the nearest cent) |
Your Turn 6.34 §6.3 source ↗
Answer
| (rounded to the nearest cent) |
Subtract the interest off the loan payment.
$700 – 9.59 = $690.41 went toward paying off the loan.
$1,400 – 690.41 = $709.59 is the remaining balance of the loan.
$709.59Your Turn 6.34 (b) §6.3 source ↗
Answer
| (rounded to the nearest cent) |
Subtract the interest off the loan payment.
$10,000 – 182.74 = $9,817.26 went toward paying off the loan.
$23,000 – 9,817.26 = $13,182.74 is the remaining balance of the loan.
$13,182.74Your Turn 6.35 §6.3 source ↗
Answer
Interest on the loan after 75 days:
Interest on the loan after 30 days:
(rounded to the nearest cent)
Subtract the partial interest off the loan payment.
$1,250 – 32.22 = $1,217.78 went toward paying off the loan.
$3,500 – 1217.78 = $2,282.22 is the remaining balance of the loan.
There are 45 more days to pay interest:
more interest will accrue.
The total payout left of the loan is the balance of the loan plus the additional interest.
$2,313.74
Your Turn 6.36 §6.3 source ↗
Answer
The amount of monthly payments, A, for a loan with principal P, monthly simple interest rate r (in decimal form), for t number of months is found using the formula . The monthly interest rate is the annual interest rate divided by 12.
5 years = 60 months
$443.90
Your Turn 6.37 §6.3 source ↗
Compute the present value of the investment described. Interpret the result.
= $25,000, = 10 years, annual simple interest rate of 7.5%Answer
The present value, PV, of money deposited at an annual, simple interest rate of r (in decimal form) for time t (in years) with a specified future value of FV is calculated with the formula . Present value, in this calculation, is always rounded up. Otherwise, the future value may fall short of the target future value.
| (rounded up to the next cent) |
$14,285.72 needs to be invested in an account earning 7.5% annual simple interest to have $25,000 at the end of the 10 years.
$14,285.72. $14,285.72 needs to be invested so that, after 10 years at 7.5% interest, the investment will be worth $25,000.Your Turn 6.37 (b) §6.3 source ↗
Compute the present value of the investment described. Interpret the result.
= $320,000, = 35 years, annual simple interest rate of 6.5%Answer
The present value, PV, of money deposited at an annual, simple interest rate of r (in decimal form) for time t (in years) with a specified future value of FV is calculated with the formula . Present value, in this calculation, is always rounded up. Otherwise, the future value may fall short of the target future value.
| (rounded up to the next cent) |
$97,709.93 needs to be invested in an account earning 6.5% annual simple interest to have $320,000 at the end of the 35 years.
$97,709.93. $97,709.93 needs to be invested so that, after 35 years at 6.5% interest, the investment will be worth $320,000.Your Turn 6.37 (c) §6.3 source ↗
Compute the present value of the investment described. Interpret the result.
= $90,000, = 270 months, annual simple interest rate of 3.75%Answer
The present value, PV, of money deposited at an annual, simple interest rate of r (in decimal form) for time t (in years) with a specified future value of FV is calculated with the formula . Present value, in this calculation, is always rounded up. Otherwise, the future value may fall short of the target future value.
270 months is 22.5 years.
| (rounded up to the next cent) |
$48,813.56 needs to be invested in an account earning 3.75% annual simple interest to have $90,000 at the end of the 22.5 years.
$48,813.56. $48,813.56 needs to be invested so that, after 270 months at 3.75% interest, the investment will be worth $90,000.Your Turn 6.38 §6.3 source ↗
Answer
The present value, PV, of money deposited at an annual, simple interest rate of r (in decimal form) for time t (in years) with a specified future value of FV is calculated with the formula . Present value, in this calculation, is always rounded up. Otherwise, the future value may fall short of the target future value.
| (rounded up to the next cent) |
Check Your Understanding 6.3.13 §6.3 source ↗
Answer
Check Your Understanding 6.3.14 §6.3 source ↗
Answer
Check Your Understanding 6.3.15 §6.3 source ↗
Answer
The interest is $1,169.10.
$1,169.10Check Your Understanding 6.3.16 §6.3 source ↗
Answer
Interest on the loan after 25 days:
| (rounded to the nearest cent) |
Subtract the partial interest off the loan payment.
$13,000 – 174.43 = $12,825.57 went toward paying off the loan.
$24,200 – 12,825.57 = $11,374.43 is the remaining balance of the loan still due.
$11,374.87Check Your Understanding 6.3.17 §6.3 source ↗
Answer
The amount of monthly payments, A, for a loan with principal P, monthly simple interest rate r (in decimal form), for t number of months is found using the formula . The monthly interest rate is the annual interest rate divided by 12.
4 years = 48 months
$266.82
Check Your Understanding 6.3.18 §6.3 source ↗
Answer
The present value, PV, of money deposited at an annual, simple interest rate of r (in decimal form) for time t (in years) with a specified future value of FV is calculated with the formula . Present value, in this calculation, is always rounded up. Otherwise, the future value may fall short of the target future value.
| (rounded up to the next cent) |
Your Turn 6.39 §6.4 source ↗
Answer
The interest is the principal times the annual simple interest rate as a decimal times the time in years .
Step 1: End of the first year
The interest is added into the account and you begin earning interest on $5,150.
Step 2: End of the second year
The interest is added into the account and you begin earning interest on $5,304.50.
Step 3: End of the third year
| (rounded) |
The interest is added into the account and you begin earning interest on $5,463.64.
Step 4: End of the fourth year
| (rounded) |
The interest is added into the account and you begin earning interest on $5,627.54.
The CD is worth $5,627.54 after 4 years.Your Turn 6.40 §6.4 source ↗
Answer
From the previous exercise, you know she earned $5,627.54 when compounded annually.
Find the amount if earning simple interest:
You earned $27.54 more when compounding interest.
CD would have been worth $5,600. Oksana earned $27.54 more with compound interest.Your Turn 6.41 §6.4 source ↗
In the following, compute the future value of the investment with the given conditions.
Principal is $7,600, annual interest rate is 4.1%, compounded monthly, for 10 years.Answer
The future value of an investment, , when the principal, , is invested at an annual interest rate of (in decimal form), compounded times per year for years is found using the formula .
Hint: Find before you plug numbers into your calculator! It will help you get the right results. Use those parentheses in your calculator, too!
$11,443.81
Your Turn 6.41 (b) §6.4 source ↗
In the following, compute the future value of the investment with the given conditions.
Principal is $13,250, annual interest rate is 2.79%, compounded quarterly, for 25 years.Answer
The future value of an investment, , when the principal, , is invested at an annual interest rate of (in decimal form), compounded times per year for years is found using the formula .
Hint: Find before you plug numbers into your calculator! It will help you get the right results. Use those parentheses in your calculator, too!
$26,551.23
Your Turn 6.42 §6.4 source ↗
Answer
The future value of an investment, , when the principal, , is invested at an annual interest rate of (in decimal form), compounded times per year for years is found using the formula .
Hint: Find before you plug numbers into your calculator! It will help you get the right results. Use those parentheses in your calculator, too!
$5,813.64
Your Turn 6.43 §6.4 source ↗
Answer
The future value of an investment, , when the principal, , is invested at an annual interest rate of (in decimal form), compounded times per year for years is found using the formula .
Hint: Find before you plug numbers into your calculator! It will help you get the right results. Use those parentheses in your calculator, too!
$3,555.88
Your Turn 6.44 §6.4 source ↗
Find the present value of the accounts under the following conditions.
= $1,000,000, invested at 5.75% interest, compounded monthly, for 40 years.Answer
The money invested in an account bearing an annual interest rate of (in decimal form), compounded times per year for years, is called the present value, , of the account (or of the money) and found using the formula where is the value of the account at the investment’s end. Always round this value up to the next penny.
Hint: Find before you plug numbers into your calculator!
$100,811.07
Your Turn 6.44 (b) §6.4 source ↗
Find the present value of the accounts under the following conditions.
= $175,000, invested at 3.8% interest, compounded quarterly, for 20 years.Answer
The money invested in an account bearing an annual interest rate of (in decimal form), compounded times per year for years, is called the present value, , of the account (or of the money) and found using the formula where is the value of the account at the investment’s end. Always round this value up to the next penny.
Hint: Find before you plug numbers into your calculator!
$82,135.75
Your Turn 6.45 §6.4 source ↗
Answer
The money invested in an account bearing an annual interest rate of (in decimal form), compounded times per year for years, is called the present value, , of the account (or of the money) and found using the formula where is the value of the account at the investment’s end. Always round this value up to the next penny.
It is 35 years until Hajun turns 65.
Hint: Find before you plug numbers into your calculator!
Hajun needs to invest $96,271.23.
$96,271.23Your Turn 6.46 §6.4 source ↗
Answer
Effective annual yield is where effective annual yield, the interest rate in decimal form, and the number of times the interest is compounded in a year. is interpreted as the equivalent annual simple interest rate.
Effective annual yield: 7.19%
Earning 7% compounded quarterly gives you an effective annual yield of 7.19%, which is the equivalent of the annual simple interest rate.
A rate of 7% compounded quarterly is equivalent to a simple interest rate of 7.19%.Your Turn 6.47 §6.4 source ↗
Answer
Effective annual yield is where effective annual yield, the interest rate in decimal form, and the number of times the interest is compounded in a year. is interpreted as the equivalent annual simple interest rate.
Effective annual yield: 2.53%
Earning 2.5% compounded daily gives you an effective annual yield of 2.53%, which is the equivalent of the annual simple interest rate.
The effective annual yield is 2.53%.Your Turn 6.48 §6.4 source ↗
| Bank | Interest Rate |
|---|---|
| Smith Bank | 3.08% compounded quarterly |
| Park Bank | 3.11% compounded annually |
| Town Bank | 3.09% compounded daily |
| Community Bank | 3.10% compounded monthly |
Answer
Find the effective annual yield of each bank.
| Smith Bank | Effective annual yield: 3.11% |
| Park Bank | Effective annual yield: 3% |
| Town Bank | Effective annual yield: 3.98% |
| Community Bank | Effective annual yield: 3.14% |
Community Bank has the highest effective annual yield at 3.14%.
The effective annual yields for the banks are 3.1158% for Smith Bank, 3.11% for Park Bank, 3.1381% for Town Bank, and 3.144% for Community Bank. Community Bank has the best yield.Check Your Understanding 6.4.19 §6.4 source ↗
Answer
Check Your Understanding 6.4.20 §6.4 source ↗
Answer
Check Your Understanding 6.4.21 §6.4 source ↗
Answer
The future value of an investment, , when the principal, , is invested at an annual interest rate of (in decimal form), compounded times per year for years is found using the formula .
Hint: Find before you plug numbers into your calculator! It will help you get the right results. Use those parentheses in your calculator, too!
$15,698.69
Check Your Understanding 6.4.22 §6.4 source ↗
Answer
Future value with simple interest:
The interest is the principal times the annual simple interest rate as a decimal times the time in years .
Future value with compound interest:
The future value of an investment, , when the principal, , is invested at an annual interest rate of (in decimal form), compounded times per year for years is found using the formula .
Hint: Find before you plug numbers into your calculator! It will help you get the right results. Use those parentheses in your calculator, too!
The difference between the two methods:
You earn $405.62 more by compounding.
$405.62Check Your Understanding 6.4.23 §6.4 source ↗
Answer
The money invested in an account bearing an annual interest rate of (in decimal form), compounded times per year for years, is called the present value, , of the account (or of the money) and found using the formula where is the value of the account at the investment’s end. Always round this value up to the next penny.
Hint: Find before you plug numbers into your calculator!
$30,266.48
Check Your Understanding 6.4.24 §6.4 source ↗
Answer
Check Your Understanding 6.4.25 §6.4 source ↗
Answer
Effective annual yield is where effective annual yield, the interest rate in decimal form, and the number of times the interest is compounded in a year. is interpreted as the equivalent annual simple interest rate.
Effective annual yield: 4.98%
4.98%Your Turn 6.49 §6.5 source ↗
Answer
| Income | Amount | Expense | Amount |
| Electrician | $3,375.00 | Mortgage | $987.00 |
| Side jobs | $300.00 | Truck payment | $589.00 |
| Truck insurance | $312.00 | ||
| Utilities | $167.00 | ||
| Clothing | $150.00 | ||
| Entertainment | $400.00 | ||
| Credit card | $325.00 | ||
| Food | $470.00 | ||
| Gasoline | $375.00 | ||
| Total | $3,675.00 | Total | $3,775.00 |
Add the income amounts:
Add the expenses:
The expenses are greater than the income by $100.
Mateo’s budget is below.| Income Source | Amount | Expense | Amount |
|---|---|---|---|
| Electrician | $3,375.00 | Mortgage | $987 |
| Side jobs | $300.00 | Truck payment | $589 |
| Truck insurance | $312 | ||
| Utilities | $167 | ||
| Clothing | $150 | ||
| Entertainment | $400 | ||
| Credit Card | $325 | ||
| Food | $470 | ||
| Gasoline | $375 |
Your Turn 6.50 §6.5 source ↗
Answer
| Income | Amount | Expense | Amount |
| Engineer | $6,093.75 | Mortgage | $1,452.89 |
| Car payment | $627.38 | ||
| Car insurance | $179.00 | ||
| Health insurance | $265.00 | ||
| Utilities | $320.00 | ||
| Clothing | $150.00 | ||
| Entertainment | $400.00 | ||
| Credit card | $450.00 | ||
| Food | $370.00 | ||
| Gasoline | $175.00 | ||
| Total | $6,093.75 | Total | $4,389.27 |
The income amount is $6,093.75.
Add the expenses:
The income is greater than the expenses by $1,704.48.
Maddy’s budget is below.| Income Source | Amount | Expense | Amount |
|---|---|---|---|
| Engineer | $6,093.75 | Mortgage | $1,452.89 |
| Car payment | $627.38 | ||
| Car insurance | $179.00 | ||
| Health Insurance | $265.00 | ||
| Utilities | $320.00 | ||
| Clothing | $150.00 | ||
| Entertainment | $400.00 | ||
| Credit Card | $450.00 | ||
| Food | $370.00 | ||
| Gasoline | $175.00 |
Her total monthly income is $6,093.75, and her monthly expenses are $4,389.27. Maddy has $1,704.48 in extra income per month. This is her cushion in the budget.
Your Turn 6.51 §6.5 source ↗
Answer
Her new budget:
| Income | Amount | Expense | Amount |
| Nursing | $3,765.40 | Mortgage | $1,240.00 |
| Part-time | $672.00 | Car payment | $489.00 |
| Student loan | $728.00 | ||
| Car insurance | $139.00 | ||
| Utilities | $295.00 | ||
| Clothing | $150.00 | ||
| Entertainment | $300.00 | ||
| Credit card | $200.00 | ||
| Food | $400.00 | ||
| Gasoline | $250.00 | ||
| Total | $4,437.40 | Total | $4,191.00 |
New income – expenses = $246.40 with the mortgage and increase in utilities.
She still has an excess in her budget.
She would change from a rent of $1,050 to a mortgage of $1,240.
This is an increase of $190.
Her utilities would also change from $130 to $295.
This is an increase of $165.
This is an overall increase of
Her budget in the example had an excess of $601.40 as a cushion. Her cushion can cover this $355 increase in expenses.
Heather’s budget is now| Income Source | Amount | Expense | Amount |
|---|---|---|---|
| Nursing | $3,765.40 | Mortgage | $1,240 |
| Part-time | $672.00 | Car Payment | $489 |
| Student Loan | $728 | ||
| Car Insurance | $139 | ||
| Utilities | $295 | ||
| Clothing | $150 | ||
| Entertainment | $300 | ||
| Credit Card | $200 | ||
| Food | $400 | ||
| Gasoline | $250 |
Your Turn 6.52 §6.5 source ↗
| Income Source | Amount | Expense | Amount |
|---|---|---|---|
| Nursing | $3,765.40 | Rent | $1,050 |
| Part-time | $672.00 | Car Payment | $489 |
| Student Loan | $728 | ||
| Car Insurance | $139 | ||
| Utilities | $130 | ||
| Clothing | $150 | ||
| Entertainment | $300 | ||
| Credit Card | $200 | ||
| Food | $400 | ||
| Gasoline | $250 |
Answer
| Income | Amount | Expense | Amount |
| Nursing | $3,765.40 | Rent | $1,050.00 |
| Part-time | $672.00 | Car payment | $489.00 |
| Student loan | $728.00 | ||
| Car insurance | $139.00 | ||
| Utilities | $130.00 | ||
| Clothing | $150.00 | ||
| Entertainment | $300.00 | ||
| Credit card | $200.00 | ||
| Food | $400.00 | ||
| Gasoline | $250.00 | ||
| Total | $4,437.40 | Total | $3,836.00 |
Income – expenses = $601.40
The 50-30-20 principle suggests spending 50 percent of your budget on necessary expenses (basic living requirements and debt services such as mortgage/rent, utilities, car, insurance, health care, groceries, gasoline, child care, and minimum debt payments), 30 percent of your budget for wants (restaurants, vacations, hobby costs), and 20 percent should be set aside (retirement funds, stocks, an emergency fund should have at least 3 months of income, other investments).
Heather’s monthly income is $4,437.40.
| 50% Needs | 30% Wants | 20% Set Aside | |
| Goal | $2,218.70 | $1,331.22 | $887.48 |
| Actual | Rent: $1,050 Car payment: $489 Student loan: $728 Car insurance: $139 Utilities: $130 Clothing: $150 Credit card: $200 Food: $400 Gasoline: $250 Total: $3536 This is above what she should have in this category. | Entertainment: $300 Total: $300 This is below what she should have in this category, but it is possible that what she charged on the credit card and clothing could be moved over to this column if you knew what it was. | Unused: $601.40 |
For the necessities, Heather should budget $2,218.70.
For her wants, she should budget $1,331.22.
For savings and extra debt service, she should budget $887.48.
Her necessities total $3,536.00, which exceeds the suggested budget amount of $2,218.70.
Her wants total $300.00, which is below the suggested budget amount of $1,331.22.
Her excess income is $601.40, which is below the suggested budget amount of $887.48.
Heather should make some changes.
Your Turn 6.53 §6.5 source ↗
Answer
The 50-30-20 principle suggests spending 50 percent of your budget on necessary expenses (basic living requirements and debt services such as mortgage/rent, utilities, car, insurance, health care, groceries, gasoline, child care, and minimum debt payments), 30 percent of your budget for wants (restaurants, vacations, hobby costs), and 20 percent should be set aside (retirement funds, stocks, an emergency fund should have at least 3 months of income, other investments).
The monthly income: $3,263.44.
Spend 50 percent on needs. Fifty percent is $1,631.72.
Spend 30 percent on wants. Thirty percent is $979.03.
Set aside 20 percent in savings, investments, and debt service. Twenty percent is $652.69.
Keeping within or below his budget can build his savings.
Elijah should budget $1,631.72 for needs, $979.03 for wants, and $652.69 for savings and debt service. When choosing where to live, what to eat, and what to drive, he should make choices that keep those costs, combined with debt service costs, gasoline, and utilities, below $1,631.72. This means he will have to make decisions about what his priorities are. Elijah should then figure out his wants, and stay within the limits here, that is, keep those costs below $979.03. Finally, he can begin to build his savings with the remaining $652.69.Your Turn 6.54 §6.5 source ↗
Fran wants to take a new job but will have to move to an area with a higher cost of living. With her current income, she can use the 50-30-20 budget philosophy. The new job will have a net pay of $43,700 annually. She will still have to pay her car payment of $295.00, her student loans that cost $264.00 per month, and her outstanding credit card debt, on which she pays $200 per month.
Apply the 50-30-20 budget philosophy to Fran’s new income.Answer
The 50-30-20 principle suggests spending 50 percent of your budget on necessary expenses (basic living requirements and debt services such as mortgage/rent, utilities, car, insurance, health care, groceries, gasoline, child care, and minimum debt payments), 30 percent of your budget for wants (restaurants, vacations, hobby costs), and 20 percent should be set aside (retirement funds, stocks, an emergency fund should have at least 3 months of income, other investments).
Monthly income = $43,700 / 12
The monthly income: $3,641.66.
Spend 50 percent on needs. Fifty percent is $1,820.83.
Spend 30 percent on wants. Thirty percent is $1,092.50.
Set aside 20 percent in savings, investments, and debt service. Twenty percent is $728.33.
Her monthly income is $3,641.66.Needs (50%): $1,820.83, Wants (30%): $1,092.50, Savings (20%): $728.33
Your Turn 6.54 (b) §6.5 source ↗
Fran wants to take a new job but will have to move to an area with a higher cost of living. With her current income, she can use the 50-30-20 budget philosophy. The new job will have a net pay of $43,700 annually. She will still have to pay her car payment of $295.00, her student loans that cost $264.00 per month, and her outstanding credit card debt, on which she pays $200 per month.
If she follows the budget, how much does she have, after paying her credit card debt, car payment and student loan, to spend on necessities.Answer
Your Turn 6.54 (c) §6.5 source ↗
Fran wants to take a new job but will have to move to an area with a higher cost of living. With her current income, she can use the 50-30-20 budget philosophy. The new job will have a net pay of $43,700 annually. She will still have to pay her car payment of $295.00, her student loans that cost $264.00 per month, and her outstanding credit card debt, on which she pays $200 per month.
If she follows the budget, how much will she set aside for wants? For savings?Answer
Spend 30 percent on wants. Thirty percent is $1,092.50.
Set aside 20 percent in savings, investments, and debt service. Twenty percent is $728.33.
$1,092.50, $728.33Your Turn 6.54 (d) §6.5 source ↗
Fran wants to take a new job but will have to move to an area with a higher cost of living. With her current income, she can use the 50-30-20 budget philosophy. The new job will have a net pay of $43,700 annually. She will still have to pay her car payment of $295.00, her student loans that cost $264.00 per month, and her outstanding credit card debt, on which she pays $200 per month.
Discuss the affordability of changing jobs and moving, based on Fran’s budget.Answer
Check Your Understanding 6.5.26 §6.5 source ↗
Answer
Check Your Understanding 6.5.27 §6.5 source ↗
Answer
Check Your Understanding 6.5.28 §6.5 source ↗
Answer
| Income | Amount | Expenses | Amount |
|---|---|---|---|
| Job | $3,450.00 | Rent | $925.00 |
| Car payment | $178.54 | ||
| Car insurance | $129.49 | ||
| Credit card | $117.00 | ||
| Gas | $195.00 | ||
| Food | $290.00 | ||
| Amazon Prime | $21.99 | ||
| Internet | $49.99 | ||
| Going out | $400.00 | ||
| Total | $2,307.01 |
Check Your Understanding 6.5.29 §6.5 source ↗
Answer
Income = $3,450
Expenses
Budget
He has $1,142.99 after accounting for expenses.
$1,142.99Check Your Understanding 6.5.30 §6.5 source ↗
Answer
The 50-30-20 principle suggests spending 50 percent of your budget on necessary expenses (basic living requirements and debt services such as mortgage/rent, utilities, car, insurance, health care, groceries, gasoline, child care, and minimum debt payments), 30 percent of your budget for wants (restaurants, vacations, hobby costs), and 20 percent should be set aside (retirement funds, stocks, an emergency fund should have at least 3 months of income, other investments).
Monthly income is $3,450.
| 50% Needs | 30% Wants | 20% Set Aside | |
| Goal | $1,725.00 | $1,035.00 | $690.00 |
| Actual | Rent: $925.00 Car payment: $178.54 Car insurance: $129.49 Credit card: $117 Gas: $195.00 Food: $290.00 Total: $1,835.03 | Amazon Prime: $21.99 Going out: $400.00 Internet: $49.99 Total: $471.98 | Unused: $1,142.99 |
Check Your Understanding 6.5.31 §6.5 source ↗
Answer
Your Turn 6.55 §6.6 source ↗
Answer
The amount in the account, A, when the principal, P, is invested at an annual interest rate of r (in decimal form), compounded n times per year for t years is found using the formula .
It will help you get the right answer from your calculator to find nt separately.
$5,952.97
Your Turn 6.56 §6.6 source ↗
Answer
The amount in the account, A, when the principal, P, is invested at an annual interest rate of r (in decimal form), compounded n times per year for t years is found using the formula .
It will help you get the right answer from your calculator to find nt separately.
$3,741.46
Your Turn 6.57 §6.6 source ↗
Answer
The amount in the account, A, when the principal, P, is invested at an annual interest rate of r (in decimal form), compounded n times per year for t years is found using the formula .
It will help you get the right answer from your calculator to find nt separately.
$8,978.57
Your Turn 6.58 §6.6 source ↗
Answer
The return on investment (ROI) is the percent difference between the initial investment (P) and the final value of the investment (FV), or , expressed as a percentage. The length of time of the investment is not considered in ROI.
17.31%
Your Turn 6.58 (b) §6.6 source ↗
Answer
The return on investment (ROI) is the percent difference between the initial investment (P) and the final value of the investment (FV), or , expressed as a percentage. The length of time of the investment is not considered in ROI.
13.2%
Your Turn 6.59 §6.6 source ↗
Answer
The future value of an ordinary annuity is , where FV is the future value of the annuity, pmt is the payment, r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. It is important to note that the number of deposits per year and the number of compounding periods per year must be the same.
It will help you get the right answer using your calculator to find first.
The extra parentheses were added to help you enter the expression properly in your calculator.
Your Turn 6.60 §6.6 source ↗
Answer
The future value of an ordinary annuity is , where FV is the future value of the annuity, pmt is the payment, r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. It is important to note that the number of deposits per year and the number of compounding periods per year must be the same.
It will help you get the right answer using your calculator to find first.
$93,037.59
Your Turn 6.61 §6.6 source ↗
Answer
To compute the payment to reach a final goal, the payment (pmt) of an ordinary annuity to reach a specific future value (FV) is , where r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. Round up!
Once again, it will help you get the right answer using your calculator to find first.
Additional parentheses were added to help you enter the expression properly in your calculator.
Check Your Understanding 6.6.32 §6.6 source ↗
Answer
Check Your Understanding 6.6.33 §6.6 source ↗
Answer
Check Your Understanding 6.6.34 §6.6 source ↗
Answer
Check Your Understanding 6.6.35 §6.6 source ↗
Answer
The future value of an investment, A, when the principal, P, is invested at an annual interest rate of r (in decimal form), compounded n times per year for t years is found using the formula .
Hint: Find nt before you plug numbers into your calculator!
It will help you get the right results. Use those parentheses in your calculator, too!
$8,549.93
Check Your Understanding 6.6.36 §6.6 source ↗
Answer
The return on investment (ROI) is the percent difference between the initial investment (P) and the final value of the investment (FV), or , expressed as a percentage. The length of time of the investment is not considered in ROI.
25.6%
Check Your Understanding 6.6.37 §6.6 source ↗
Answer
The future value of an ordinary annuity is , where FV is the future value of the annuity, pmt is the payment, r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. It is important to note that the number of deposits per year and the number of compounding periods per year must be the same.
It will help you get the right answer using your calculator to find first.
The extra parentheses were added to help you enter the expression properly in your calculator.
Check Your Understanding 6.6.38 §6.6 source ↗
Answer
To compute the payment to reach a final goal, the payment (pmt) of an ordinary annuity to reach a specific future value (FV) is , where r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. Round up!
Once again, it will help you get the right answer using your calculator to find first.
Additional parentheses were added to help you enter the expression properly in your calculator.
Your Turn 6.62 §6.7 source ↗
Answer
Use your knowledge of percents. Remember to convert the percentage to a decimal.
3.1% of 500
Maureen receives $237.50 per year.
On the maturity date, she receives the interest and the initial payment.
$237.50 per year, $5,237.50 on maturity date.
Your Turn 6.63 §6.7 source ↗
Answer
Use the formula for the future value of an investment, A, when the principal, P, is invested at an annual interest rate of r (in decimal form), compounded n times per year for t years: .
Hint: Find nt before you plug numbers into your calculator!
It will help you get the right results. Use those parentheses in your calculator, too!
Rixie expects the stock to be worth $108,501.30.
$108,501.30Your Turn 6.64 §6.7 source ↗
Answer
The percent yield for a stock, Yld%, is .
4.28%
Your Turn 6.64 (b) §6.7 source ↗
Answer
The percent yield for a stock, Yld%, is .
3.29%
Your Turn 6.65 §6.7 source ↗
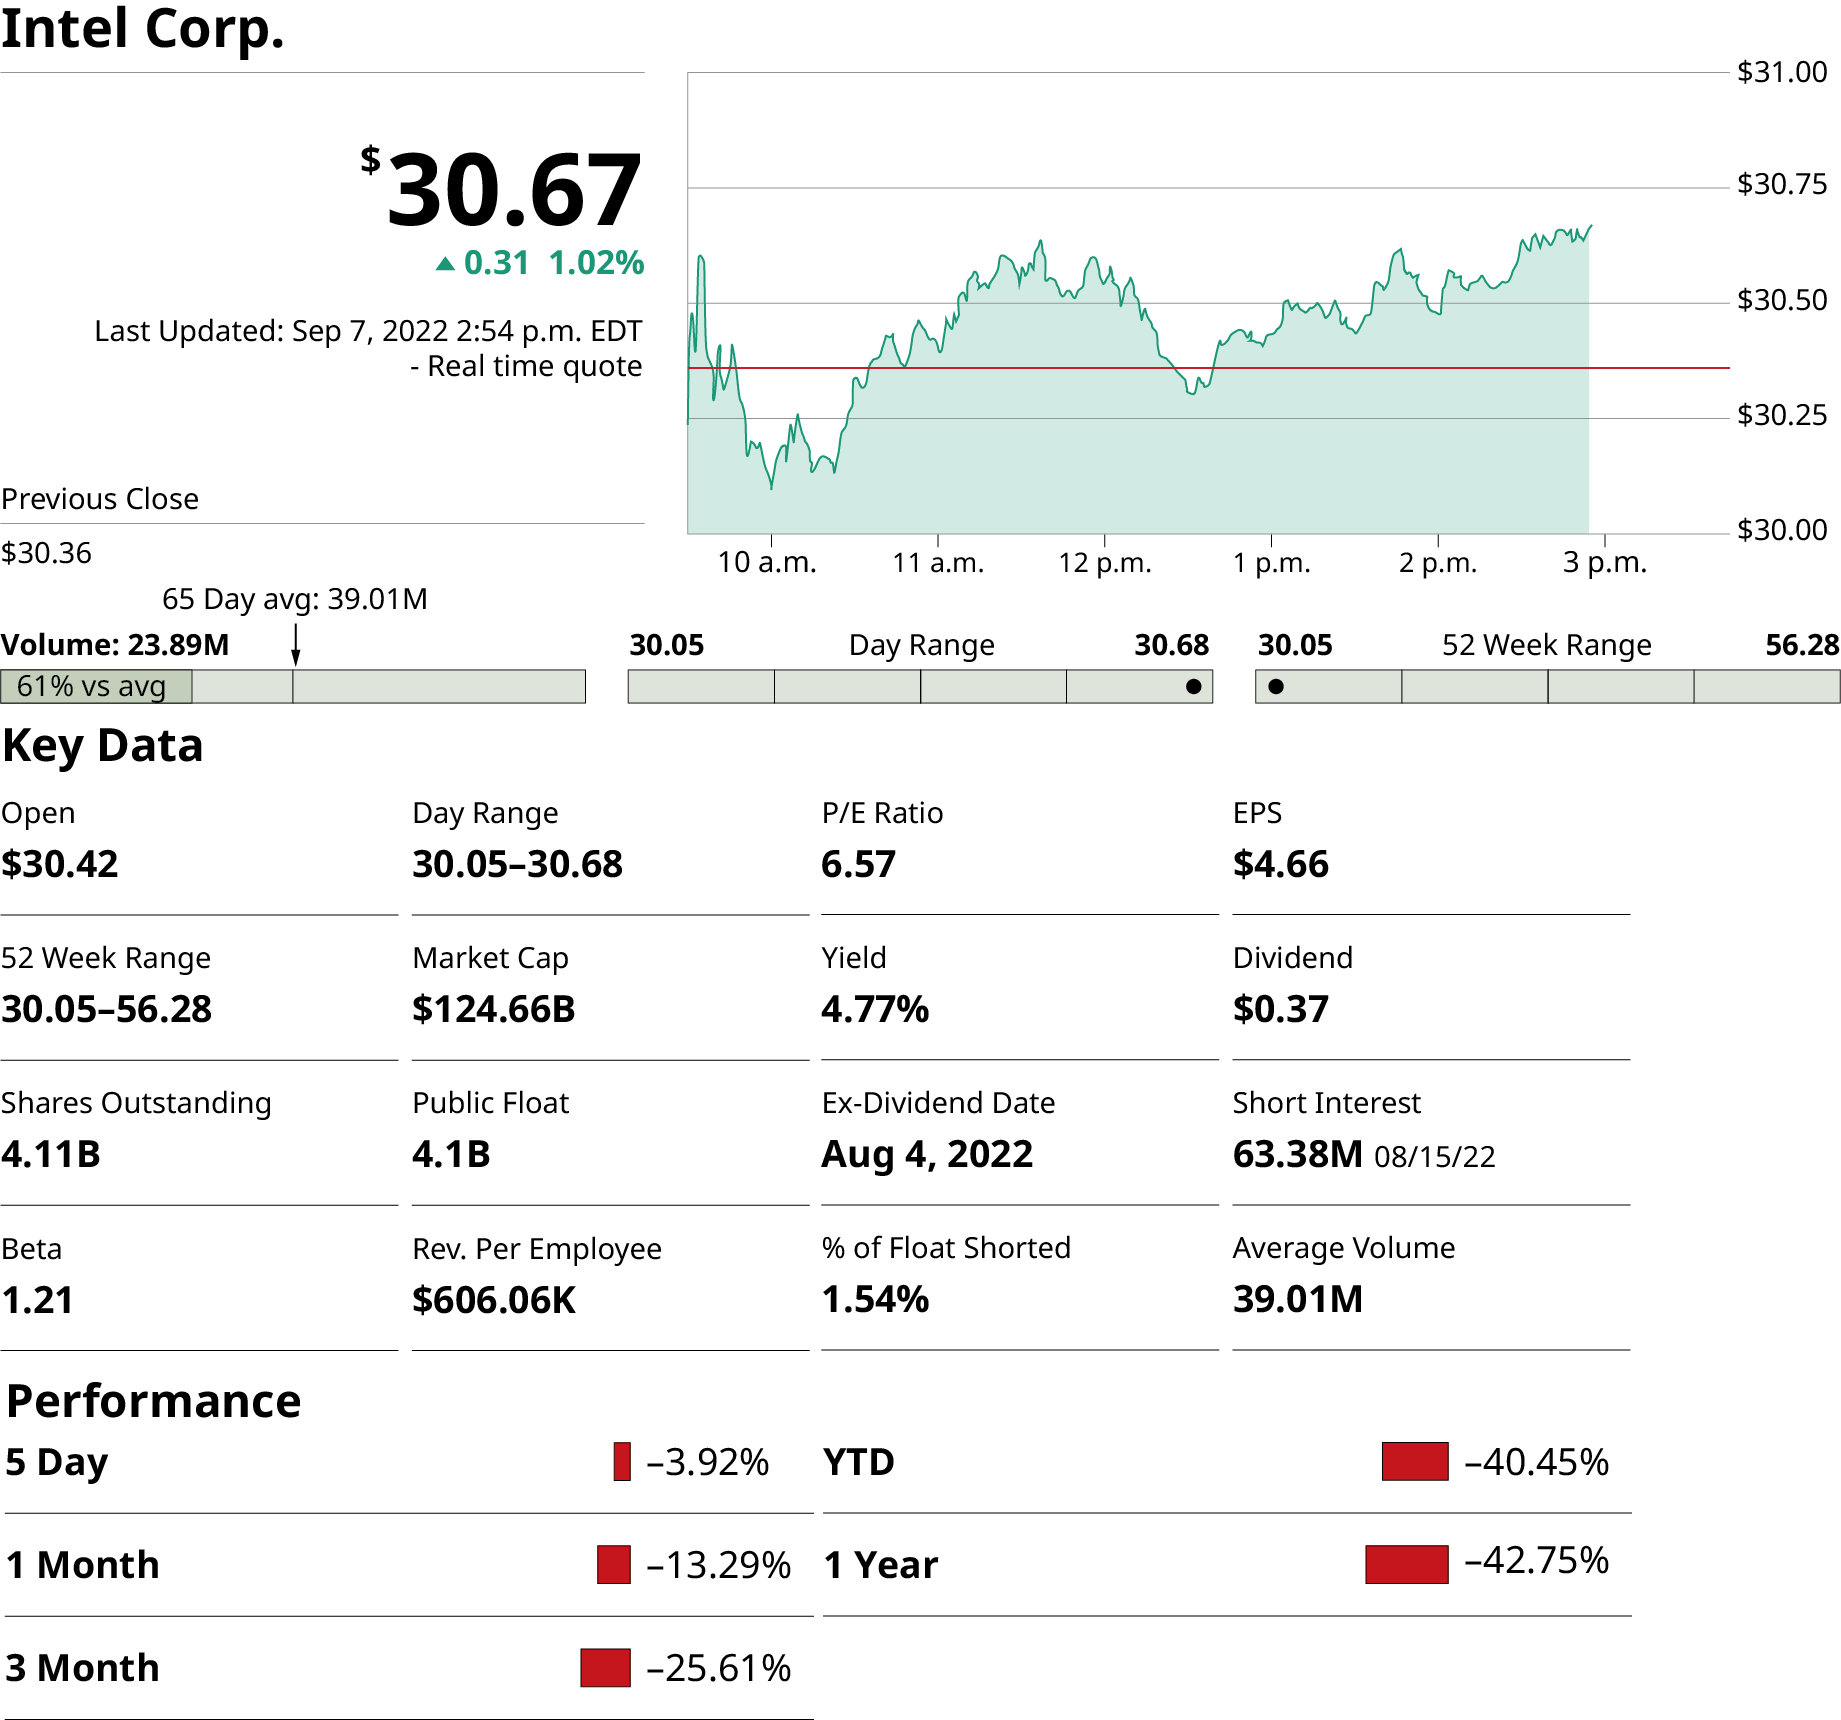
 Key data for Intel stock 9/7/2022 (data source: marketwatch.com) What is the current price for Intel Corp on this date?
Answer
Your Turn 6.65 (b) §6.7 source ↗
Key data for Intel stock 9/7/2022 (data source: marketwatch.com) What is the 52-wk high? 52-wk low?Answer
Your Turn 6.65 (c) §6.7 source ↗
Key data for Intel stock 9/7/2022 (data source: marketwatch.com) When is the dividend expected?Answer
Your Turn 6.65 (d) §6.7 source ↗
Key data for Intel stock 9/7/2022 (data source: marketwatch.com) What is its yield?Answer
Your Turn 6.65 (e) §6.7 source ↗
Key data for Intel stock 9/7/2022 (data source: marketwatch.com) What is the earnings per share?Answer
Your Turn 6.66 §6.7 source ↗
Answer
Each share pays $1.12.
Because the number of shares is 300, multiply 300 by $1.12.
Yulia earns $336.
Your Turn 6.67 §6.7 source ↗
Ginny buys 200 shares of stock in UUK company for $9.76 per share. At the end of the year, she sells those stocks for $10.02 per share.
How much money did Ginny make?Answer
Ginny bought 200 shares of stock at $9.76 per share: .
Later, 200 shares sold for $10.02 per share: .
$52
Your Turn 6.67 (b) §6.7 source ↗
Ginny buys 200 shares of stock in UUK company for $9.76 per share. At the end of the year, she sells those stocks for $10.02 per share.
What was her return on investment for that one year?Answer
The return on investment (ROI) is the percent difference between the initial investment (P) and the final value of the investment (FV), or , expressed as a percentage. The length of time of the investment is not considered in ROI.
2.6%
Your Turn 6.68 §6.7 source ↗
Answer
The future value is , where FV is the future value, pmt is the payment, r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. It is important to note that the number of deposits per year and the number of compounding periods per year must be the same.
It will help you get the right answer using your calculator to find first.
The extra parentheses were added to help you enter the expression properly in your calculator.
$108,352.43Your Turn 6.69 §6.7 source ↗
Answer
To compute the payment to reach a final goal, the payment (pmt) of an ordinary annuity or mutual fund to reach a specific future value (FV) is , where r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. Round up!
Once again, it will help you get the right answer using your calculator to find first.
Additional parentheses were added to help you enter the expression properly in your calculator.
Your Turn 6.70 §6.7 source ↗
Answer
Each year, Maureen was paid 4.75% of the $5,000 she invested.
Maureen is paid interest each year for five years.
The return on investment (ROI) is the percent difference between the initial investment (P) and the final value of the investment (FV), or , expressed as a percentage. The length of time of the investment is not considered in ROI.
Your Turn 6.71 §6.7 source ↗
Answer
Maureen’s FV is the $5,000 she invested plus the $1,187.50 she earned for a total of $6,187.50. Her principal was $5,000. The time is 5 years.
The annual return , where t is the number of years, FV is the new value, and P is the starting principal. Convert the answer to a percent.
annual return
Maureen’s annual return on investment is 4.35 percent.
4.35%Your Turn 6.72 §6.7 source ↗
Rixie deposits $23,000 in the stock of DEF company. After 12 years, her stock is worth $108,501.30.
What is Rixie’s return on investment?Answer
The return on investment (ROI) is the percent difference between the initial investment (P) and the final value of the investment (FV), or , expressed as a percentage. The length of time of the investment is not considered in ROI.
Rixie’s ROI is 371.74 percent.6.72.2
371.74%Your Turn 6.72 (b) §6.7 source ↗
Rixie deposits $23,000 in the stock of DEF company. After 12 years, her stock is worth $108,501.30.
What is Rixie’s annual return?Answer
The annual return , where t is the number of years, FV is the new value, and P is the starting principal. Convert the answer to a percent.
annual return
The annual return was 13.8 percent.
13.8%Your Turn 6.73 §6.7 source ↗
Answer
To compute the payment to reach a final goal for an annuity or mutual fund, the payment (pmt) is , where r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. Round up!
Once again, it will help you get the right answer using your calculator to find first.
Additional parentheses were added to help you enter the expression properly in your calculator.
Pete and Erin need to set aside $3,336.13 each year.
Your Turn 6.74 §6.7 source ↗
Answer
Your Turn 6.75 §6.7 source ↗
Jameis signs up for his employer-based 401(k). The employer matches any 401(k) contribution up to 7.5% of the employee salary. Jameis’ annual salary is $72,800.
What is the most money that Jamie can deposit that will be fully matched by the company?Answer
An employer will match up to 7.5% of any employee’s salary.
The amount Jamie can deposit that will be matched by the employer is $5,460.
$5,460Your Turn 6.75 (b) §6.7 source ↗
Jameis signs up for his employer-based 401(k). The employer matches any 401(k) contribution up to 7.5% of the employee salary. Jameis’ annual salary is $72,800.
How much total will be deposited into Jameis’ account if he deposits the full 7.5%?Answer
The amount Jamie deposits plus the employer’s match: .
The total is $10,920.
$10,920Your Turn 6.75 (c) §6.7 source ↗
Jameis signs up for his employer-based 401(k). The employer matches any 401(k) contribution up to 7.5% of the employee salary. Jameis’ annual salary is $72,800.
How much return does Jameis earn if he deposits exactly 7.5% in her 401(k)?Answer
Jamie deposits $5,460. The account ends up with $10,920.
The return on investment (ROI) is the percent difference between the initial investment (P) and the final value of the investment (FV), or , expressed as a percentage. The length of time of the investment is not considered in ROI.
The ROI is 100%.
100% return on the $5,460 depositYour Turn 6.76 §6.7 source ↗
Crystal begins depositing $450 per month from her paycheck each month in her employer-based 401(k) account. The employer matches $350 of each deposit. Crystal expects the return to average 9% per year, compounded annually.
How much will Crystal’s account be worth if she keeps making those payments for 25 years?Answer
The future value of an ordinary annuity or mutual fund is , where FV is the future value of the annuity, pmt is the payment, r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. It is important to note that the number of deposits per year and the number of compounding periods per year must be the same.
It will help you get the right answer using your calculator to find first.
The combined monthly payment is .
It is only compounded annually, so for the payment, multiply the monthly payment by 12.
The extra parentheses were added to help you enter the expression properly in your calculator.
Crystal’s account will be worth $813,128.60.
Your Turn 6.76 (b) §6.7 source ↗
Crystal begins depositing $450 per month from her paycheck each month in her employer-based 401(k) account. The employer matches $350 of each deposit. Crystal expects the return to average 9% per year, compounded annually.
What will her account be worth without the matching funds?Answer
It is only compounded annually, so for the payment, multiply the monthly payment by 12.
Without matching funds, her account will be worth $457,384.84.
Check Your Understanding 6.7.39 §6.7 source ↗
Answer
Stocks are the highest risk of what was studied in the lesson. Bonds, stocks, and mutual funds tend to offer higher returns, but to varying degrees, come with higher risks.
Bonds are considered a conservative investment. They are bought for what is known as the issue price. The interest is fixed (does not change) at the time of purchase and is based on the issue price of the bond. The interest rate is often referred to as the coupon rate; the interest paid is often called the coupon yield. The interest paid is often higher than savings accounts and the risk is exceptionally low.
Stocks are part ownership in a company. They come in units called shares. The performance and earnings of stocks is not guaranteed, which makes them riskier than any other investment discussed earlier. However, they can offer higher return on investment than the other investments. An important thing to remember is that stocks might provide a very large return on investment, but the trade-off is the risk associated with owning stocks.
A mutual fund is a collection of investments that are all bundled together. When you buy shares of a mutual fund, your money is pooled with the assets of other investors. Because there are many different investments inside the mutual fund, the risk is reduced significantly, compared to direct ownership of stocks.
Your employer may offer a retirement account to you. These are often in the form of a 401(k) account. There are traditional and Roth 401(k) accounts, which differ in how they are taxed, much as with other IRAs. These accounts are similar to mutual funds, in that the money is invested in a wide range of assets, spreading the risk.
StocksCheck Your Understanding 6.7.40 §6.7 source ↗
Answer
Check Your Understanding 6.7.41 §6.7 source ↗
Answer
Check Your Understanding 6.7.42 §6.7 source ↗
Answer
Use your knowledge of percents. Remember to convert the percentage to a decimal.
Each year, they receive $200 for 10 years.
Over the 10 years, they receive in total.
Each year, the holder of the bond receives $200. For 10 years, that’s $2,000 total earned with the bond.Check Your Understanding 6.7.43 §6.7 source ↗
Answer
Check Your Understanding 6.7.44 §6.7 source ↗
Answer
Find 4% of $87,500.
Merisol can deposit up to $3,500 for her employer to match the amount. If she deposits more, the employer will not match it.
$3,500, which is 4% of her incomeCheck Your Understanding 6.7.45 §6.7 source ↗
Answer
300 shares times $0.38 per share
The person earns $114.
$114.00Check Your Understanding 6.7.46 §6.7 source ↗
Answer
The annual return , where t is the number of years, FV is the new value, and P is the starting principal. Convert the answer to a percent.
annual return
David’s annual return on that investment was 9.93%.
9.93%Check Your Understanding 6.7.47 §6.7 source ↗
Answer
To compute the payment to reach a final goal for an annuity or mutual fund, the payment (pmt) is , where r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. Round up!
Once again, it will help you get the right answer using your calculator to find first.
Additional parentheses were added to help you enter the expression properly in your calculator.
The annual payment must be $5,207.59.
$5,207.59Your Turn 6.77 §6.8 source ↗
Find the interest to be paid for the period on loans with the following remaining principal and given annual interest rate. Each period is a month.
Remaining principal is $56,945, interest rate is 7.5%Answer
The amount of interest, I, to be paid for one period of a loan with remaining principal, P, is , where r is the interest rate in decimal form and n is the number of payments in a year. Because r is the interest rate in a year, t is 1 and does not impact the calculation. Note, interest paid to lenders is always rounded up to the nearest penny.
$355.91
Your Turn 6.77 (b) §6.8 source ↗
Find the interest to be paid for the period on loans with the following remaining principal and given annual interest rate. Each period is a month.
Remaining principal is $25,850, interest rate is 2.9%Answer
The amount of interest, I, to be paid for one period of a loan with remaining principal, P, is , where r is the interest rate in decimal form and n is the number of payments in a year. Because r is the interest rate in a year, t is 1 and does not impact the calculation. Note, interest paid to lenders is always rounded up to the nearest penny.
$62.48
Your Turn 6.78 §6.8 source ↗
In the following, calculate the payment necessary to pay off the loan with the given details. The payments are monthly.
A home improvement loan taken out for $17,950 at an annual interest rate of 7.5% for 10 years.Answer
To compute the payment to pay down a loan with beginning principal, P, the payment (pmt) is , where r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. Note, payment to lenders is always rounded up to the next penny.
Once again, it will help you get the right answer from your calculator to find first.
Additional parentheses were added to help you enter the expression properly in your calculator.
The payment is $213.07.
$213.07Your Turn 6.78 (b) §6.8 source ↗
In the following, calculate the payment necessary to pay off the loan with the given details. The payments are monthly.
A solar panel installation loan taken out for $33,760 and an annual interest rate of 4.3% for 20 years.Answer
To compute the payment to pay down a loan with beginning principal, P, the payment (pmt) is , where r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. Note, payment to lenders is always rounded up to the next penny.
Once again, it will help you get the right answer from your calculator to find first.
Additional parentheses were added to help you enter the expression properly in your calculator.
The payment is $209.96.
$209.96Your Turn 6.79 §6.8 source ↗
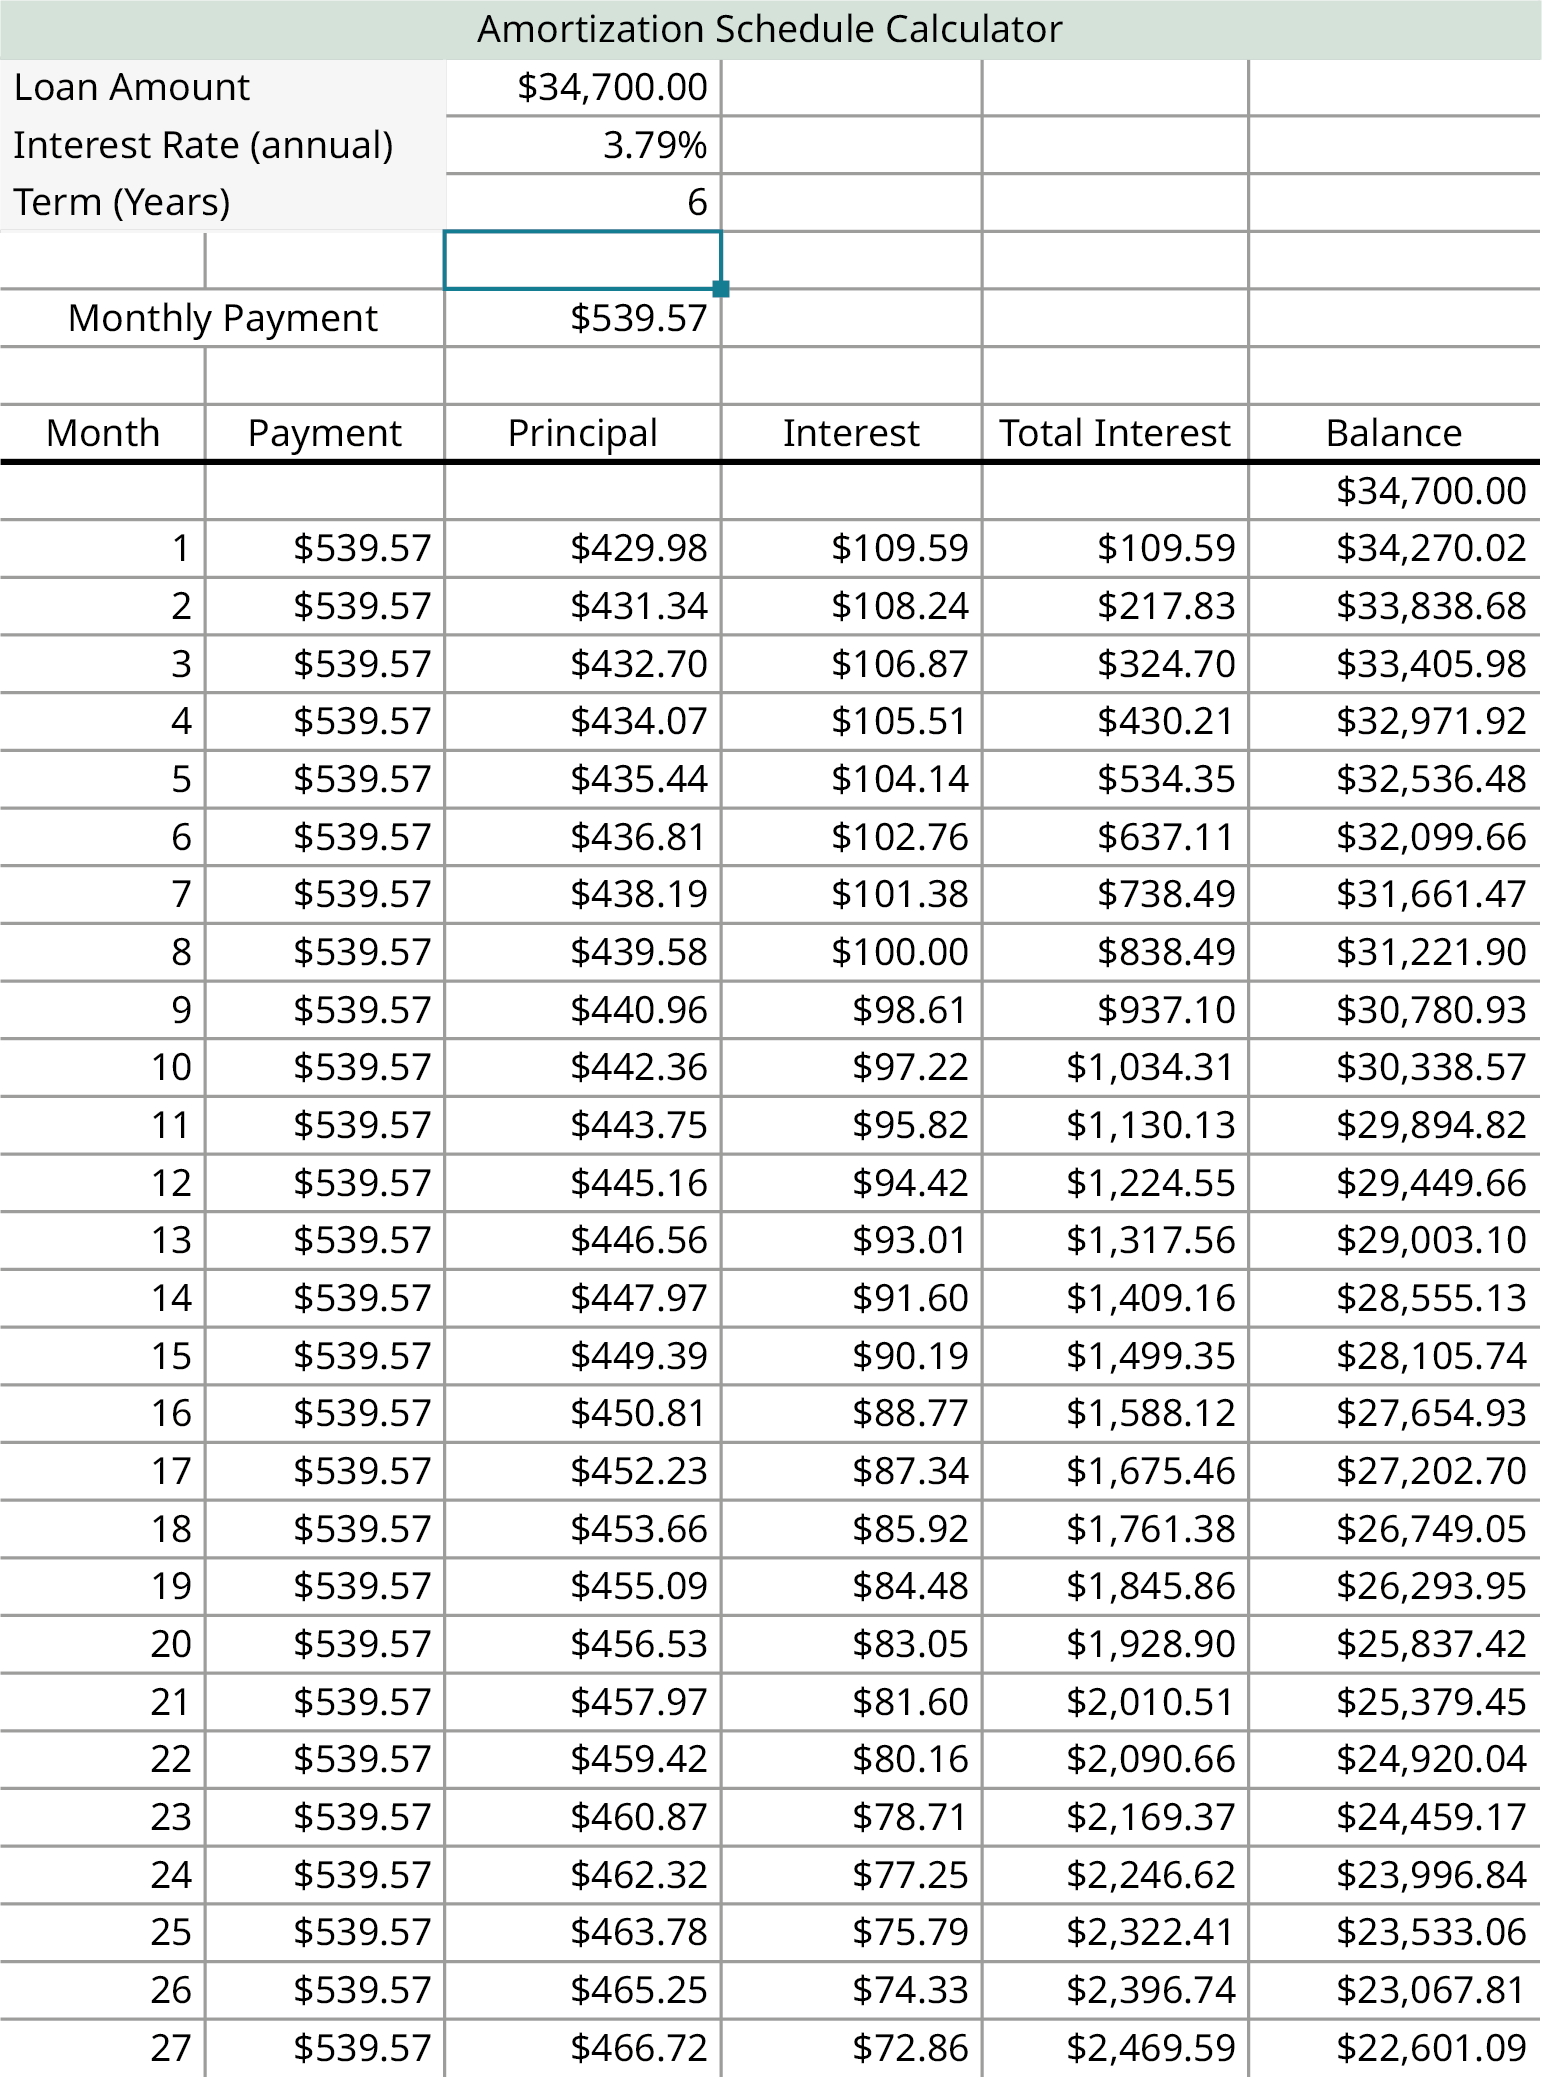 Amortization table What is the loan amount (principal), the interest rate, and the term of the loan?
Answer
Look at the top row. The label to the left says “Loan Amount.” To the right, you see the loan amount, $34,700. This is usually called the principal in the formulas.
Look for the label called “Interest Rate (annual)” in the second row. Beside it, you see the interest rate of 3.79%.
Look for the label in the third row called “Term (Years).” Beside it, you see the number of years for the loan, which is 6 years.
$34,700, 3.79%, 6 yearsYour Turn 6.79 (b) §6.8 source ↗
Amortization table How much is the monthly payment?Answer
Your Turn 6.79 (c) §6.8 source ↗
Amortization table How much remaining balance is there after the payment in month 20?Answer
In the seventh row, first column, you see the header title, “Month.” In the last column on the right, you see the header title, “Balance.”
Scroll down in the first column to find Month 20. While in that row, look across to the last column in that row to find the balance is $25,837.42.
$25,837.42Your Turn 6.79 (d) §6.8 source ↗
Amortization table How much was the interest in payment 5?Answer
In the seventh row, second column, you see the header title, “Month.” In the fourth column of that row, you see the header title, “Interest.”
Look down the first column for Month 5. While in that row, look across to the fourth column of that row to see that the interest for Month 5 is $104.14.
$104.14Your Turn 6.79 (e) §6.8 source ↗
Amortization table What is the total of the interest paid after payment 24?Answer
In the seventh row, second column, you see the header title, “Month.” In the fifth column of that row, you see the header title, “Total Interest.”
Look down the first column for Month 24. While in that row, look across to the fifth column of that row to see that the total interest for Month 24 is $2,246.62.
$2,246.62Your Turn 6.79 (f) §6.8 source ↗
Amortization table What happens to the amount paid to the principal each month?Answer
Your Turn 6.80 §6.8 source ↗
Answer
The cost of finance is the sum of the interest and any fees paid for the loan. Add that to the interest.
$6,437.18
Check Your Understanding 6.8.48 §6.8 source ↗
Answer
Check Your Understanding 6.8.49 §6.8 source ↗
Answer
Check Your Understanding 6.8.50 §6.8 source ↗
Answer
Check Your Understanding 6.8.51 §6.8 source ↗
Answer
The amount of interest, I, to be paid for one period of a loan with remaining principal, P, is , where r is the interest rate in decimal form, n is the number of payments in a year, and t is the time in years.
$59.11
Check Your Understanding 6.8.52 §6.8 source ↗
Answer
To compute the payment to pay down a loan with beginning principal, P, the payment (pmt) is , where r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. Note, payment to lenders is always rounded up to the next penny.
Once again, it will help you get the right answer from your calculator to find first.
$2,233.12
Check Your Understanding 6.8.53 §6.8 source ↗
Answer
Check Your Understanding 6.8.54 §6.8 source ↗
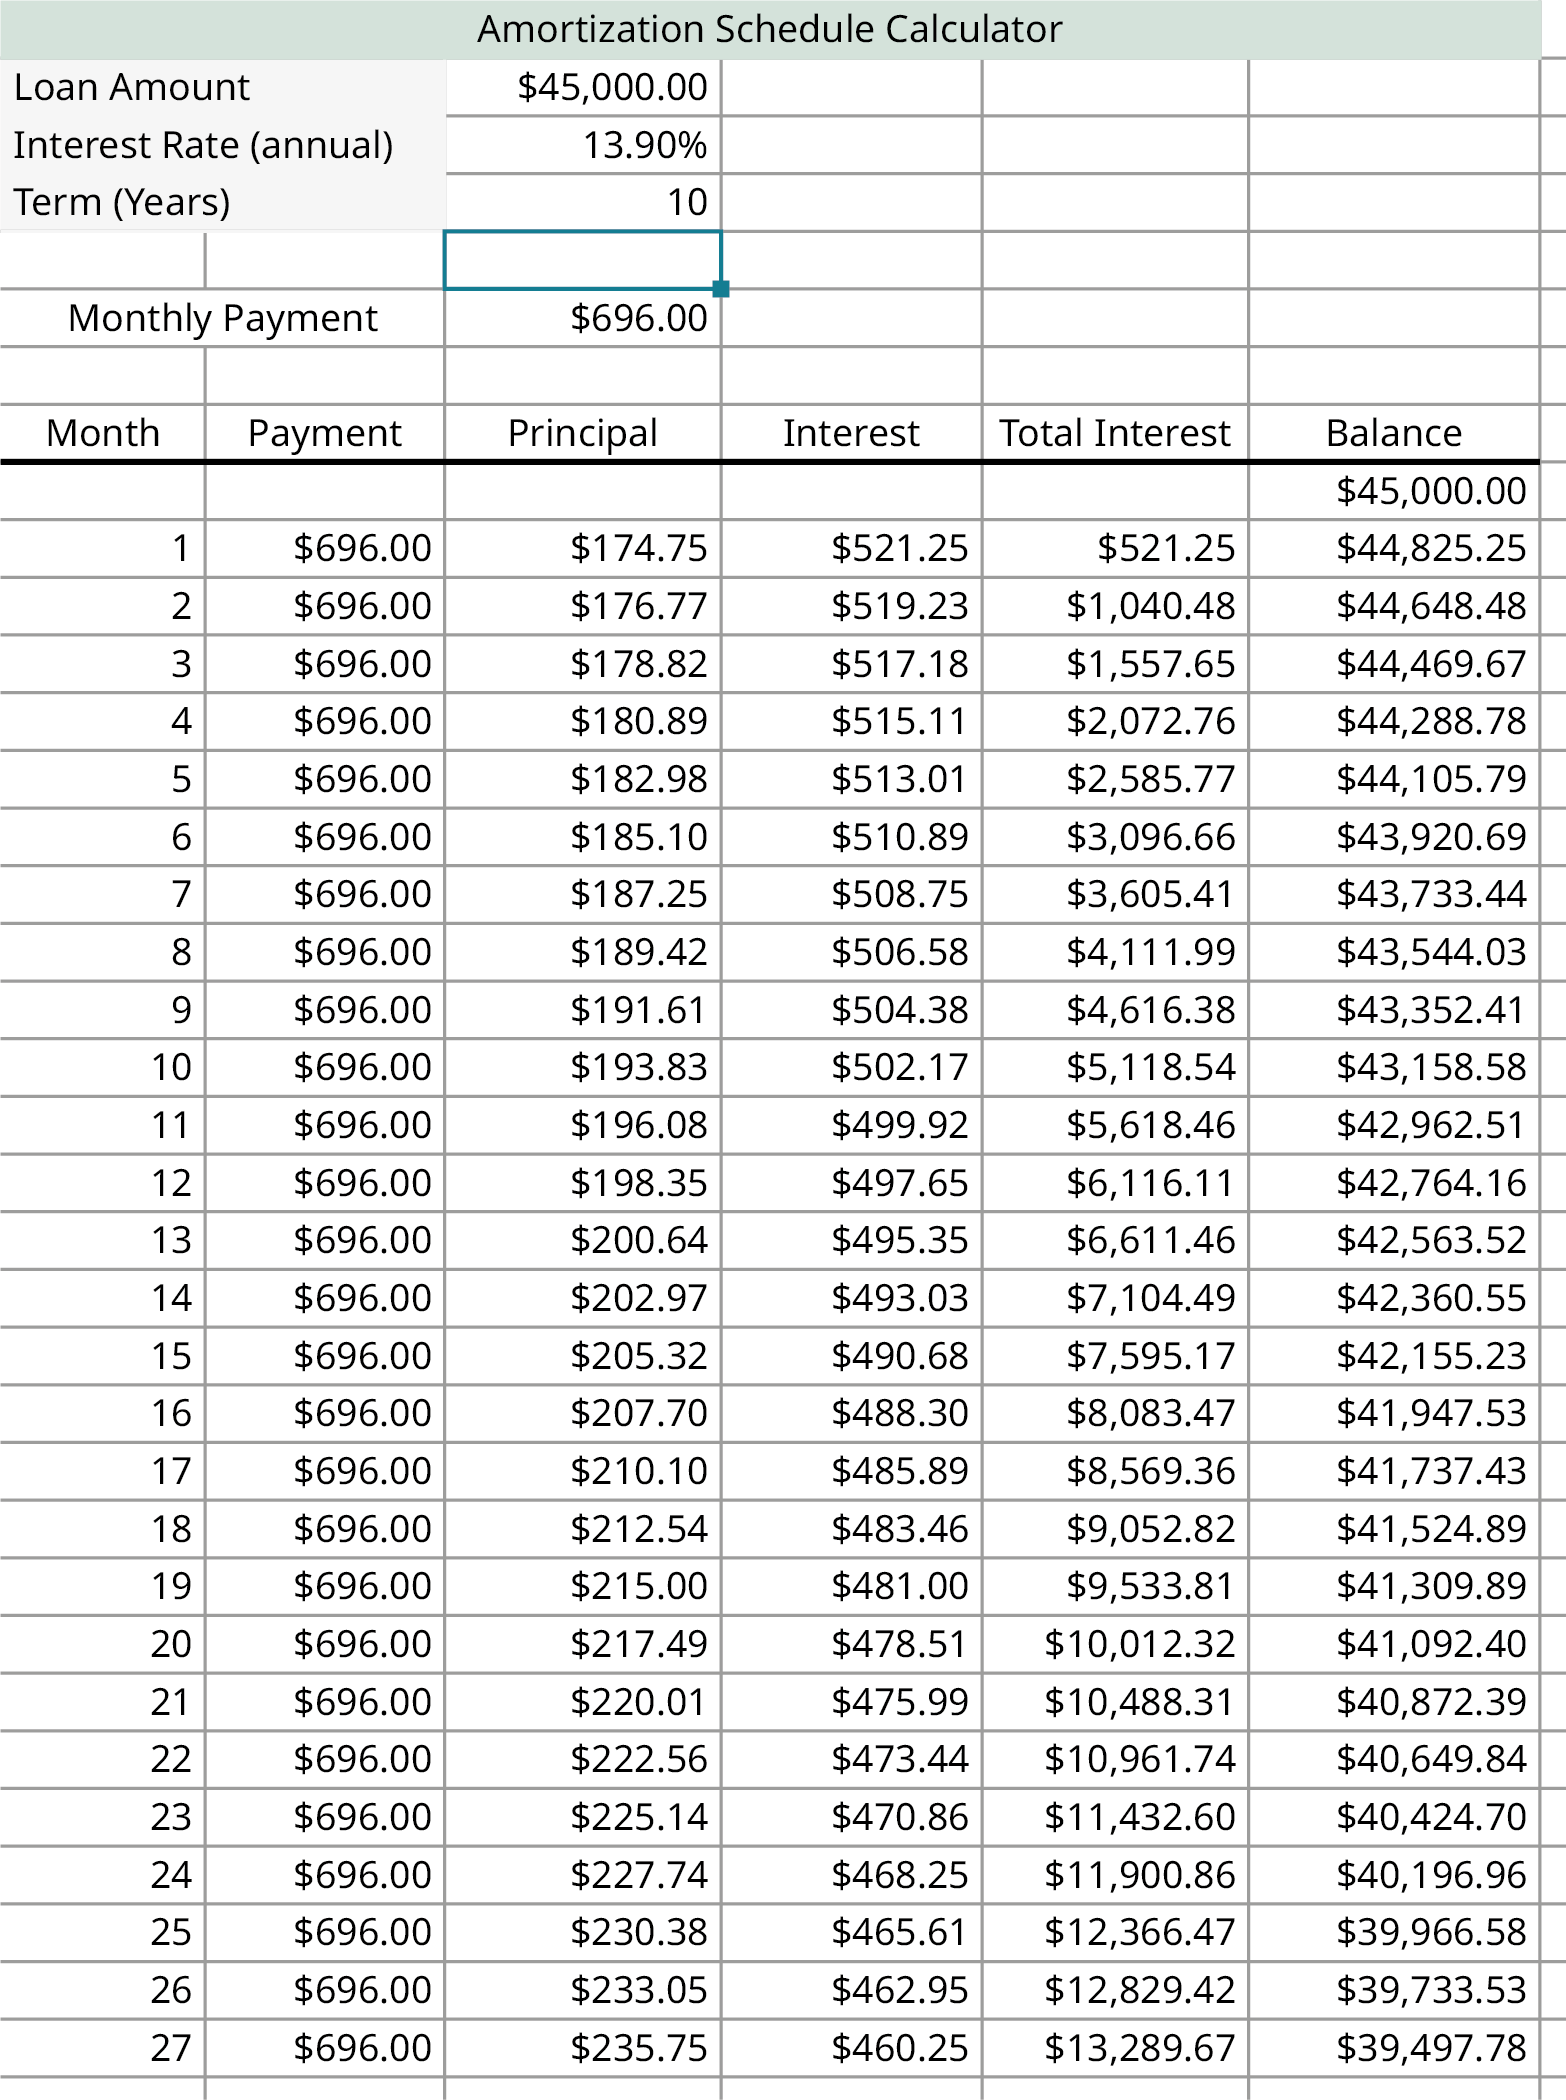
Answer
The cost of finance is the sum of all interest and any fees paid for the loan. Add that to the interest.
$39,544.50
Your Turn 6.81 §6.9 source ↗
Answer
The costs are $34,845.
The awards are .
The funding gap is $9,745.
$9,745Your Turn 6.82 §6.9 source ↗
Answer
The debt so far:
Tiana is an independent student, so for the first year, she can borrow $9,500. For the second year, she can borrow $10,500. For additional years, she can borrow $12,500.
The total maximum for undergraduates is $57,500.
How much can she still borrow? .
Tiana still is $13,740 away from the total allowed maximum, so she can borrow the yearly maximum of $12,500 in her sixth year.
Tiana can take out $12,500, the maximum in year 6.Your Turn 6.83 §6.9 source ↗
Answer
The costs are $39,200 for the third year.
The awards are .
The funding gap is $10,850.
Assuming that Makenzy is a dependent student, the loan limit for a third-year student is $7,500 (but no more than $5,500 in subsidized loans).
After the maximum amount of loans, find the remaining amount to be funded.
Makenzy needs to come up with another $3,350 to fund her education.
Gap = $10,850, Federal loans = $7,500, Remaining $3,350Your Turn 6.84 §6.9 source ↗
Answer
The amount due for a loan, A, when the principal, P, an interest rate of r (in decimal form), compounded n times per year for t years is found using the formula .
Hint: Find nt before you plug numbers into your calculator! It will help you get the right results.
if paid the full six years.
But they are asking for the balance in May when starting in August, so subtract three payments.
Use those parentheses in your calculator, too!
$2,987.63
Your Turn 6.85 §6.9 source ↗
Find the payment for the following student loans using the standard repayment plan:
Loan is $7,800, interest is 4.99%Answer
The standard plan is 12 payments a year for 10 years.
To compute the payment to pay down a loan with beginning principal, P, the payment (pmt) is , where r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. Note, payment to lenders is always rounded up to the next penny.
If the number of periods per year is 1, then the formula is simplified to .
Once again, it will help you get the right answer from your calculator to find first.
Additional parentheses were added to help you enter the expression properly in your calculator.
Your Turn 6.85 (b) §6.9 source ↗
Find the payment for the following student loans using the standard repayment plan:
Loan is for $11,450, interest is 7.75%Answer
The standard plan is 12 payments a year for 10 years.
To compute the payment to pay down a loan with beginning principal, P, the payment (pmt) is , where r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. Note, payment to lenders is always rounded up to the next penny.
If the number of periods per year is 1, then the formula is simplified to .
Once again, it will help you get the right answer from your calculator to find first.
Additional parentheses were added to help you enter the expression properly in your calculator.
Your Turn 6.86 §6.9 source ↗
Answer
The standard plan is 12 payments a year for 10 years.
To compute the payment to pay down a loan with beginning principal, P, the payment (pmt) is , where r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. Note, payment to lenders is always rounded up to the next penny.
If the number of periods per year is 1, then the formula is simplified to .
Once again, it will help you get the right answer from your calculator to find first.
Additional parentheses were added to help you enter the expression properly in your calculator.
$259.69Your Turn 6.87 §6.9 source ↗
Answer
Your Turn 6.88 §6.9 source ↗
Answer
The standard plan is 12 payments a year for 10 years.
To compute the payment to pay down a loan with beginning principal, P, the payment (pmt) is , where r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. Note, payment to lenders is always rounded up to the next penny.
If the number of periods per year is 1, then the formula is simplified to .
Once again, it will help you get the right answer from your calculator to find first.
Additional parentheses were added to help you enter the expression properly in your calculator.
$188.03Your Turn 6.89 §6.9 source ↗
Answer
150 percent of the poverty guideline is: .
Discretionary income is the amount Jamie earns over $31,590.
Subtract $31,590 from Jamie’s income of $36,900 to find her discretionary income.
Jamie’s discretionary income is $5,310.
$5,310Your Turn 6.90 §6.9 source ↗
Lauren, a Missouri resident, qualifies for a REPAYE payment plan. Her gross income is $39,200. She has one child, so there are two people in her household. The federal poverty guideline for Lauren is $18,310.
What is Lauren’s discretionary income?Answer
REPAYE plans have payment amounts that are 10% of discretionary income.
Discretionary income is the excess of 150% of the poverty guideline.
| Find 150 percent of $18,310: | . |
| Discretionary income is the excess over $27,465: | . |
Lauren’s discretionary income is $11,735.
$11,735Your Turn 6.90 (b) §6.9 source ↗
Lauren, a Missouri resident, qualifies for a REPAYE payment plan. Her gross income is $39,200. She has one child, so there are two people in her household. The federal poverty guideline for Lauren is $18,310.
Under the REPAYE plan, she pays 10% of her discretionary income, but monthly. How much are Lauren’s REPAYE payments?Answer
| Ten percent of her discretionary income of $11,735 is: | . |
| Divide by 12 to find the monthly payment: | . |
Lauren’s monthly payment is $97.80.
$97.80Check Your Understanding 6.9.55 §6.9 source ↗
Answer
Check Your Understanding 6.9.56 §6.9 source ↗
Answer
Check Your Understanding 6.9.57 §6.9 source ↗
Answer
Check Your Understanding 6.9.58 §6.9 source ↗
Answer
Check Your Understanding 6.9.59 §6.9 source ↗
Answer
Check Your Understanding 6.9.60 §6.9 source ↗
Answer
The amount due for a loan, A, when the principal, P, an interest rate of r (in decimal form), compounded n times per year for t years is found using the formula .
You are told the number of compounding periods.
Use those parentheses in your calculator, too!
$13,028.61
Check Your Understanding 6.9.61 §6.9 source ↗
Answer
Check Your Understanding 6.9.62 §6.9 source ↗
Answer
Your Turn 6.91 §6.10 source ↗
Answer
Your Turn 6.91 (b) §6.10 source ↗
Answer
Your Turn 6.91 (c) §6.10 source ↗
Answer
Your Turn 6.92 §6.10 source ↗
Referring to the statement above, answer the following:
What is the statement period?Answer
Look at the upper-right corner of the statement for the label “Statement Period.” Underneath the label, you will see the start date of the period after “From” and the end date of the period after “To.”
From April 01, 2015
To April 30, 2015
April 01 2015 to April 30 2015Your Turn 6.92 (b) §6.10 source ↗
Referring to the statement above, answer the following:
What is the credit limit?Answer
Your Turn 6.92 (c) §6.10 source ↗
Referring to the statement above, answer the following:
How much in fees were charged?Answer
Just above the “Your New Balance” label is the label “Subtotal.”
Above the “Subtotal” label is the label “Fees.” The fees are $5.99.
$5.99Your Turn 6.93 §6.10 source ↗
| Date | Activity | Amount |
|---|---|---|
| 1-Jun | Balance | $563.80 |
| 2-Jun | Gasoline | $47.50 |
| 2-Jun | Groceries | $63.42 |
| 15-Jun | Movie | $38.75 |
| 15-Jun | Payment | $250.00 |
| 27-Jun | Pharmacy | $31.21 |
| 28-Jun | Auto fuel | $48.00 |
Find the average daily balance for this credit card.
Answer
Use a list of transactions.
Step 1: Create a table that has the sum of transactions for each day. Expenditures are positive. Payments are negative.
Step 2: Add a column, “Days Until Balance Changed,” where you write the number of days until the balance changed. This is the difference between the date of this row and the next.
Step 3: Add a column, “Balance Times Days,” where you multiply the previous two columns.
Step 4: Sum the last column.
Step 5: Divide the sum by the number of days in the month. This is the average daily balance.
| Date | Activity | Transaction | Balance | Days Until Balance Changed | Balance Times Days |
| 1-Jun | Balance | 563.8 | 563.8 | 1 | 563.8 |
| 2-Jun | Gas-Groceries | 110.92 | 674.72 | 13 | 8771.36 |
| 15-Jun | Movie-payment | –211.25 | 463.47 | 12 | 5561.64 |
| 27-Jun | Pharmacy | 31.21 | 494.68 | 1 | 494.68 |
| 28-Jun | Gas | 48 | 542.68 | 3 | 1628.04 |
The average daily balance is the sum of the last column divided by the number of days in the month.
The average daily balance = is approximately $567.32.
$567.32Your Turn 6.94 §6.10 source ↗
Compute the interest charged for the credit card based on the given average daily balance (ABD), annual interest rate, and number of days in the billing cycle.
ADB = $2,135.00, annual interest rate 12.9%, billing cycle of 30 daysAnswer
The interest charge, I, for a credit card during a billing cycle is , where ADB is the average daily balance, r is the annual percentage rate as a decimal, and d is the number of days in the billing cycle. As before, interest is rounded up to the next penny.
$22.64
Your Turn 6.94 (b) §6.10 source ↗
Compute the interest charged for the credit card based on the given average daily balance (ABD), annual interest rate, and number of days in the billing cycle.
ADB = $1,589.63, annual interest rate 9.99%, billing cycle of 31 daysAnswer
The interest charge, I, for a credit card during a billing cycle is , where ADB is the average daily balance, r is the annual percentage rate as a decimal, and d is the number of days in the billing cycle. As before, interest is rounded up to the next penny.
$13.49
Your Turn 6.94 (c) §6.10 source ↗
Compute the interest charged for the credit card based on the given average daily balance (ABD), annual interest rate, and number of days in the billing cycle.
ADB = $6,803.41, annual interest rate 14.9%, billing cycle of 28 daysAnswer
The interest charge, I, for a credit card during a billing cycle is , where ADB is the average daily balance, r is the annual percentage rate as a decimal, and d is the number of days in the billing cycle. As before, interest is rounded up to the next penny.
$77.77
Your Turn 6.95 §6.10 source ↗
Find the balance on the credit card with the given interest charge and balance before interest was charged. The cards were not paid off previously.
Balance before interest is $560.00, interest charge is $6.44Answer
Your Turn 6.95 (b) §6.10 source ↗
Find the balance on the credit card with the given interest charge and balance before interest was charged. The cards were not paid off previously.
Balance before interest is $3,218.00, interest charge is $49.17Answer
Your Turn 6.96 §6.10 source ↗
| Date | Activity | Amount |
|---|---|---|
| 1-Aug | Billing Date Balance | $982.45 |
| 5-Aug | Food | $125.31 |
| 13-Aug | Payment | $500.00 |
| 14-Aug | Gasoline | $51.65 |
| 14-Aug | Pizza | $36.99 |
| 14-Aug | Shoes | $89.45 |
| 19-Aug | Electric bill | $178.34 |
| 21-Aug | Internet | $36.99 |
| 21-Aug | Food | $93.45 |
| 30-Aug | Gasoline | $43.18 |
Answer
Find the average daily balance.
Use a list of transactions.
Step 1: Create a table that has the sum of transactions for each day. Expenditures are positive. Payments are negative.
Step 2: Add a column, “Days Until Balance Changed,” where you write the number of days until the balance changed. This is the difference between the date of this row and the next.
Step 3: Add a column, “Balance Times Days,” where you multiply the previous two columns.
| Date | Activity | Transaction | Balance | Days Until Balance Changed | Balance Times Days |
| 1-Aug | Balance | $982.45 | $982.45 | 4 | $3,929.80 |
| 5-Aug | Food | $125.31 | $1,107.76 | 8 | $8,862.08 |
| 13-Aug | Payment | –$500.00 | $607.76 | 1 | $607.76 |
| 14-Aug | Gas/Pizza/Shoes | $178.09 | $785.85 | 5 | $3,929.25 |
| 19-Aug | Electric Bill | $178.34 | $964.19 | 2 | $1,928.38 |
| 21-Aug | Internet/Food | $130.44 | $1,094.63 | 9 | $9,851.67 |
| 30-Aug | Gasoline | $43.18 | $1,137.81 | 2 | $1,137.81 |
Step 4: Sum the last column.
$31,384.56
Step 5: Divide the sum by the number of days in the month. This is the average daily balance.
The average daily balance (ADB) is $1,012.41.
The interest charge, I, for a credit card during a billing cycle is , where ADB is the average daily balance, r is the annual percentage rate as a decimal, and d is the number of days in the billing cycle. As before, interest is rounded up to the next penny.
Add the interest to the last balance in the table.
Your Turn 6.97 §6.10 source ↗
The CLH credit card company has the following minimum payment policy. For balances over $1,000, the minimum payment is 1% of the balance due plus interest and fees. For balances between $25.00 and $999.99, the minimum payment is $25.00 plus any fees. For balances under $25.00, the minimum payment is the balance due plus any fees.
In the following, calculate the minimum payment due given the credit card minimum payment policy, the balance due and fees charged.
Answer
For this amount, use 1 percent plus interest plus fees. There are no fees.
One percent plus interest is: .
$47.47Your Turn 6.97 (b) §6.10 source ↗
The CLH credit card company has the following minimum payment policy. For balances over $1,000, the minimum payment is 1% of the balance due plus interest and fees. For balances between $25.00 and $999.99, the minimum payment is $25.00 plus any fees. For balances under $25.00, the minimum payment is the balance due plus any fees.
In the following, calculate the minimum payment due given the credit card minimum payment policy, the balance due and fees charged.
Answer
For this amount, use $25 interest plus fees.
$84.00
Your Turn 6.97 (c) §6.10 source ↗
The CLH credit card company has the following minimum payment policy. For balances over $1,000, the minimum payment is 1% of the balance due plus interest and fees. For balances between $25.00 and $999.99, the minimum payment is $25.00 plus any fees. For balances under $25.00, the minimum payment is the balance due plus any fees.
In the following, calculate the minimum payment due given the credit card minimum payment policy, the balance due and fees charged.
Answer
Check Your Understanding 6.10.63 §6.10 source ↗
Answer
Check Your Understanding 6.10.64 §6.10 source ↗
Answer
Check Your Understanding 6.10.65 §6.10 source ↗
Answer
Check Your Understanding 6.10.66 §6.10 source ↗
Answer
The interest charge, I, for a credit card during a billing cycle is , where ADB is the average daily balance, r is the annual percentage rate as a decimal, and d is the number of days in the billing cycle. As before, interest is rounded up to the next penny.
$19.30
Check Your Understanding 6.10.67 §6.10 source ↗
| Date | Activity | Amount |
|---|---|---|
| 15-Jun | Billing Date Balance | $3,825.50 |
| 20-Jun | Food | $125.31 |
| 20-Jun | Clothing | $345.00 |
| 29-Jun | Payment | $750.00 |
| 1-Jul | Restaurant | $94.80 |
| 6-Jul | Gasoline | $49.75 |
| 6-Jul | Home Repair Supplies | $683.94 |
| 6-Jul | Internet | $49.99 |
| 10-Jul | Cell Phone | $85.00 |
| 10-Jul | Food | $175.24 |
Answer
Use a list of transactions.
Step 1: Create a table that has the sum of transactions for each day. Expenditures are positive. Payments are negative.
Step 2: Add a column, “Days Until Balance Changed,” where you write the number of days until the balance changed. This is the difference between the date of this row and the next.
Step 3: Add a column, “Balance Times Days,” where you multiply the previous two columns.
| Date | Activity | Transaction | Balance | Days Until Balance Changed | Balance Times Days |
| 15-Jun | Balance | $3,825.50 | $3,825.50 | 5 | $19,127.50 |
| 20-Jun | Food/Clothing | $470.31 | $4,295.81 | 9 | $38,662.29 |
| 29-Jun | Payment | –$750.00 | $3,545.81 | 2 | $7,091.62 |
| 1-Jul | Restaurant | $94.80 | $3,640.61 | 5 | $18,203.05 |
| 6-Jul | Gas/Repair/Int | $783.68 | $4,424.29 | 4 | $17,697.16 |
| 10-Jul | Cell/Food | $260.24 | $4,684.53 | 5 | $23,422.65 |
$124,204.27
Step 5: Divide the sum by the number of days in the month. This is the average daily balance.
The average daily balance (ADB) is $4,140.14.
$4,104.27Check Your Understanding 6.10.68 §6.10 source ↗
Answer
First, find the interest.
The interest charge, I, for a credit card during a billing cycle is , where ADB is the average daily balance, r is the annual percentage rate as a decimal, and d is the number of days in the billing cycle. As before, interest is rounded up to the next penny.
Add the interest to the balance at the end of the billing cycle.
Your Turn 6.98 §6.11 source ↗
Answer
Add 8% and 2.1% for a total percentage of 10.1%.
Find 10.1% of $28,975.
Add this to the cost and fees.
$33,838.48
Your Turn 6.99 §6.11 source ↗
Answer
Find 6.5% of $36,250.
Add this to the cost and fees.
The car’s total cost is 40,277.75.
Subtract the $7,500 down payment to get $32,777.75.
$32,777.75Your Turn 6.100 §6.11 source ↗
In the following, calculate the monthly payment using the given total to be financed, the interest rate, and the term of the car loan.
Total to be financed is $18,325, interest rate is 6.75%, for 4 years.Answer
To compute the payment to pay down a loan with beginning principal, P, the payment (pmt) is , where r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. Note, payment to lenders is always rounded up to the next penny.
Once again, it will help you get the right answer from your calculator to find first.
Additional parentheses were added to help you enter the expression properly in your calculator.
$436.70Your Turn 6.100 (b) §6.11 source ↗
In the following, calculate the monthly payment using the given total to be financed, the interest rate, and the term of the car loan.
Total to be financed is $41,633, interest rate is 3.9%, for 6 years.Answer
To compute the payment to pay down a loan with beginning principal, P, the payment (pmt) is , where r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. Note, payment to lenders is always rounded up to the next penny.
Once again, it will help you get the right answer from your calculator to find first.
Additional parentheses were added to help you enter the expression properly in your calculator.
$649.47Your Turn 6.101 §6.11 source ↗
Answer
Your Turn 6.102 §6.11 source ↗
Answer
Add the values together.
$10,567.00
Your Turn 6.103 §6.11 source ↗
Answer
The monthly depreciation for a car, MD, is , where P is the price paid for the car, R is the residual value of the car, and n is the number of months of the lease.
$401.05
Your Turn 6.104 §6.11 source ↗
Answer
Your Turn 6.104 (b) §6.11 source ↗
Answer
The money factor (MF) is , where APR is the annual percentage rate as a decimal.
Your Turn 6.105 §6.11 source ↗
Calculate the lease payments for car with the following price, residual price, length of lease, and money factor or APR.
Price is $38,750, residual price is $18,140.16, 36-month lease, money factor is 0.000035.Answer
Your Turn 6.105 (b) §6.11 source ↗
Calculate the lease payments for car with the following price, residual price, length of lease, and money factor or APR.
Price is $45,600, residual price is $21,312.50, 24-month lease, APR is 11.7%.Answer
You need to find the money factor first.
The money factor (MF) is , where APR is the annual percentage rate as a decimal.
The payment, PMT, for a lease is , where P is the price paid for the car, R is the residual value of the car after the n months of the lease, and MF is the money factor of the lease.
$1,015.25
Your Turn 6.106 §6.11 source ↗
Answer
Your Turn 6.106 (b) §6.11 source ↗
Answer
Your Turn 6.107 §6.11 source ↗
Answer
Your Turn 6.107 (b) §6.11 source ↗
Answer
Your Turn 6.108 §6.11 source ↗
Answer
Divide the $2,190 cost per year by 12 to get $182.50.
Add that to the monthly car payment of $410.86 to get the total monthly cost of $593.36.
$593.36Your Turn 6.109 §6.11 source ↗
Answer
| Item | Cost | Calculations | Yearly cost |
| New tires every five years | $390 | 78 | |
| Oil changes every three months | $59.99 | Every three months is four times a year. | 239.96 |
| Inspections once a year | $25 | 25 | |
| Wipers once a year | $115 | 115 | |
| Air filter once a year | $46.25 | 46.25 | |
| Yearly Total: | 504.21 |
Divide the yearly total to find the monthly total is $42.02.
Natalie needs $42.02 to cover these costs.
$42.02Check Your Understanding 6.11.69 §6.11 source ↗
Answer
Check Your Understanding 6.11.70 §6.11 source ↗
Answer
Check Your Understanding 6.11.71 §6.11 source ↗
Answer
To compute the payment to pay down a loan with beginning principal, P, the payment (pmt) is , where r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. Note, payment to lenders is always rounded up to the next penny.
Once again, it will help you get the right answer from your calculator to find first.
Additional parentheses were added to help you enter the expression properly in your calculator.
$628.89Check Your Understanding 6.11.72 §6.11 source ↗
Answer
Check Your Understanding 6.11.73 §6.11 source ↗
Answer
Check Your Understanding 6.11.74 §6.11 source ↗
Answer
There are 36 months in 3 years.
The monthly depreciation for a car, MD, is , where P is the price paid for the car, R is the residual value of the car, and n is the number of months of the lease.
$333.34
Check Your Understanding 6.11.75 §6.11 source ↗
Answer
The annual percentage rate (APR) is APR = 2400 × MF, where MF is the money factor of the lease and the APR is calculated as a decimal.
Check Your Understanding 6.11.76 §6.11 source ↗
Answer
Check Your Understanding 6.11.77 §6.11 source ↗
Answer
Your Turn 6.110 §6.12 source ↗
Answer
To compute the payment to pay down a loan with beginning principal, P, the payment (pmt) is , where r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. Note, payment to lenders is always rounded up to the next penny.
Once again, it will help you get the right answer from your calculator to find first.
Additional parentheses were added to help you enter the expression properly in your calculator.
$949.72Your Turn 6.111 §6.12 source ↗
Answer
In the previous exercise, you found the monthly payment was $949.72.
The total paid, T, on a t year mortgage with monthly payments pmt is .
Arthur pays $319,620.60 in total.
$319,620.60Your Turn 6.112 §6.12 source ↗
Answer
Your Turn 6.113 §6.12 source ↗
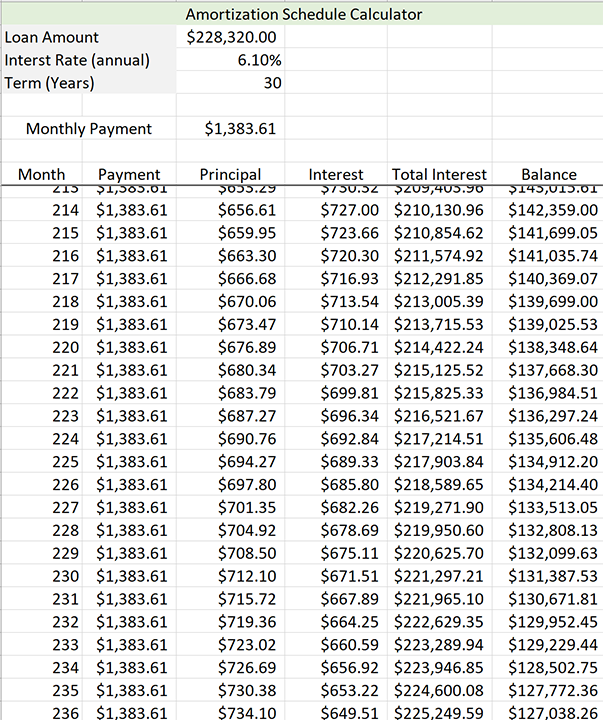 Amortization table What is the interest rate?
Answer
Your Turn 6.113 (b) §6.12 source ↗
Amortization table How much are the payments?Answer
Your Turn 6.113 (c) §6.12 source ↗
Amortization table How much of payment 235 goes to principal?Answer
Your Turn 6.113 (d) §6.12 source ↗
Amortization table How much of payment 215 goes to interest?Answer
Your Turn 6.113 (e) §6.12 source ↗
Amortization table What’s the remaining balance on the mortgage after payment 227?Answer
Your Turn 6.113 (f) §6.12 source ↗
Amortization table At what payment does the amount that is applied to mortgage finally exceed the amount applied to interest?Answer
Your Turn 6.114 §6.12 source ↗
Answer
Find her payment using the loan formula. Find the property tax and divide that by 12. Divide her insurance by 6. Add all three of those amounts to find how much Destiny pays each month.
Find her payment.
To compute the payment to pay down a loan with beginning principal, P, the payment (pmt) is , where r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. Note, payment to lenders is always rounded up to the next penny.
Once again, it will help you get the right answer from your calculator to find first.
Additional parentheses were added to help you enter the expression properly in your calculator.
Find her property tax.
Divide her property tax by 12.
Divide her insurance by 6.
Add the payment, property tax, and insurance to find the monthly payment.
$1,521.20
Check Your Understanding 6.12.78 §6.12 source ↗
Answer
Check Your Understanding 6.12.79 §6.12 source ↗
Answer
Check Your Understanding 6.12.80 §6.12 source ↗
Answer
Check Your Understanding 6.12.81 §6.12 source ↗
Answer
Check Your Understanding 6.12.82 §6.12 source ↗
Answer
To compute the payment to pay down a loan with beginning principal, P, the payment (pmt) is , where r is the annual interest rate (in decimal form), n is the number of compounding periods per year, and t is the number of years. Note, payment to lenders is always rounded up to the next penny.
Once again, it will help you get the right answer from your calculator to find first.
Additional parentheses were added to help you enter the expression properly in your calculator.
$663.32Check Your Understanding 6.12.83 §6.12 source ↗
Answer
In the previous exercise, you found the monthly payment was $663.32.
The total paid, T, on a t year mortgage with monthly payments pmt is .
The total paid is $238,795.20.
Subtract the cost of the house from the total paid to find the cost of financing.
$129,802.20
Check Your Understanding 6.12.84 §6.12 source ↗
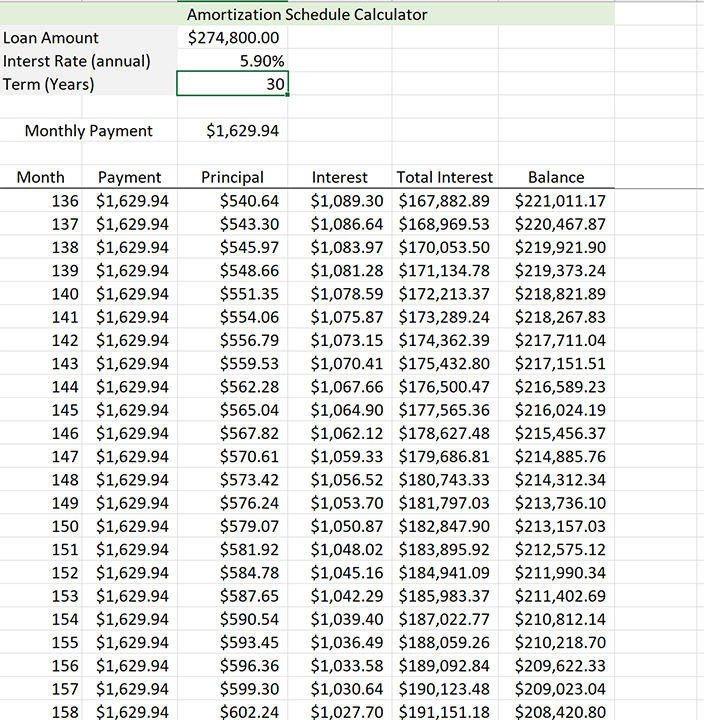
Answer
Check Your Understanding 6.12.85 §6.12 source ↗
Answer
Your Turn 6.115 §6.13 source ↗
Answer
Add the amounts to find the gross income.
41,780 + 5,500 = $47,280
$47,280Your Turn 6.116 §6.13 source ↗
Answer
Add the deductions: 7,840 + 3,810 + 1,500 = $13,150.
Subtract the legal deductions from the gross income to find the adjustable gross income (AGI).
93,450 – 31,150 = $80,300
The AGI is $80,300.
$80,300Your Turn 6.117 §6.13 source ↗
Answer
Exemptions need to be subtracted from the adjusted gross income (AGI) to find the taxable income.
43,100 – 3,400 = $39,700
The taxable income is $39,700.
$39,700Your Turn 6.118 §6.13 source ↗
Answer
Add the tax credits.
1,925 + 2,000 = 3,925
Tax credits are subtracted from the tax you owe.
3,950 – 3,925 = $25
The amount of taxes owed after applying tax credits is $25.
$25Your Turn 6.119 §6.13 source ↗
Answer
Your Turn 6.120 §6.13 source ↗
Answer
FICA stands for Federal Insurance Contributions Act of 1935. FICA taxes fund Social Security and Medicare and are automatically withdrawn from your pay. You pay 7.65 percent of your gross pay and your employer matches your amount. Of the 7.65 percent, 6.2 percent goes to Social Security (SSI) and 1.45 percent goes to Medicare. The Social Security (SSI) part only applies to the first $147,000 of your earnings, but the Medicare tax applies to all your gross earnings.
$3,200 per two-week pay period
3,200(26) = $83,200
This is under $147,000, so it is all taxable by both components of FICA.
Find 7.65% of $3,200 to find the FICA contribution.
0.0765(3,200) = $244.80 goes to FICA
Find 6.2% of $3,200 to find the SSI part:
0.062(3,200) = $198.40 to SSI
FICA is $244.80, SSI is $198.40Your Turn 6.121 §6.13 source ↗
Answer
FICA stands for Federal Insurance Contributions Act of 1935. FICA taxes fund Social Security and Medicare and are automatically withdrawn from your pay. You pay 7.65 percent of your gross pay and your employer matches your amount. Of the 7.65 percent, 6.2 percent goes to Social Security (SSI) and 1.45 percent goes to Medicare. The Social Security (SSI) part only applies to the first $147,000 of your earnings, but the Medicare tax applies to all your gross earnings.
Only the first $147,000 is taxed for SSI. Ignore the excess.
Find 6.2% of $147,000 to find the SSI part.
0.062(147,000) = $9,114 to SSI
$9,114Your Turn 6.122 §6.13 source ↗
Answer
Make your own tax table and write in the taxable income where it belongs in the table.
Add two columns.
Add a column where you subtract the upper income limit from the lower income limit. Notice that in the last row you’ve entered the taxable income for THIS exercise.
In the last column, multiply the amount you just wrote in the fifth column times the tax rate. If you know how to use spreadsheet formulas, you can multiply the cell in column 4 times the cell in column 5 to find the cell in column 6 in Google Sheets.
Delete the rows you are not using.
Add the amounts in the last column to find the total tax paid is $11,787.
| Tax Paid: | $11,787 | ||||
| Bracket | Lower Income Limit | Upper Income Limit | Tax Rate | Upper – Lower | (Upper – Lower) × Rate |
| 1 | 0 | $10,275 | 10% | $10,275 | $1,028 |
| 2 | $10,276 | $41,775 | 12% | $31,499 | $3,780 |
| 3 | $41,776 | $73,500 | 22% | $31,724 | $6,979 |
Your Turn 6.123 §6.13 source ↗
Answer
Check Your Understanding 6.13.86 §6.13 source ↗
Answer
Check Your Understanding 6.13.87 §6.13 source ↗
Answer
Check Your Understanding 6.13.88 §6.13 source ↗
Answer
Add the deductions: 2,000 + 3,000 + 8,000 = 13,000.
Subtract the legal deductions from the gross income to find the adjustable gross income (AGI).
50,000 – 13,000 = $37,000
The AGI is $37,000.
$37,000Check Your Understanding 6.13.89 §6.13 source ↗
Answer
Check Your Understanding 6.13.90 §6.13 source ↗
Answer
Check Your Understanding 6.13.91 §6.13 source ↗
Answer
Make your own tax table and write in the taxable income where it belongs in the table.
Add two columns.
Add a column where you subtract the upper income limit from the lower income limit. Notice that in the last row you’ve entered the taxable income for THIS exercise. If you know how to use spreadsheet formulas, you can have Google Sheets do the subtraction.
In the last column, multiply the amount you just wrote in the fifth column times the tax rate. If you know how to use spreadsheet formulas, you can multiply the cell in column 4 times the cell in column 5 to find the cell in column 6 in Google Sheets.
Add the amounts in the last column to find the total tax paid is $4,812.66 or $4,813 if you round.
Delete the rows you are not using.
Did you know that when you e-file taxes, the amount you pay is always rounded to dollars?
| Tax Owed: | $4,812.66 | ||||
| Bracket | Lower Income Limit | Upper Income Limit | Tax Rate | Upper – Lower | (Upper – Lower) * Rate |
| 1 | 0 | $10,275 | 10% | $10,275 | $1,027.50 |
| 2 | $10,276 | $41,775 | 12% | $31,499 | $3,779.88 |
| 3 | $41,776 | $41,800 | 22% | $24 | $5.28 |
Check Your Understanding 6.13.92 §6.13 source ↗
Answer
Subtract the tax credits to find the amount of tax owed.
5,600 – 4,000 = $1,600
$1,600Loading chapter 7…
Problems and answers are adapted from Contemporary Mathematics by Donna Kirk, OpenStax, and are used under the CC BY-NC-SA 4.0 licence. Access for free at https://openstax.org/books/contemporary-mathematics/pages/1-introduction. Illustrations: Copyright Rice University, OpenStax, under CC BY-NC-SA 4.0 license. This adaptation is released under the same licence, is non-commercial, and is neither affiliated with nor endorsed by OpenStax or Rice University.